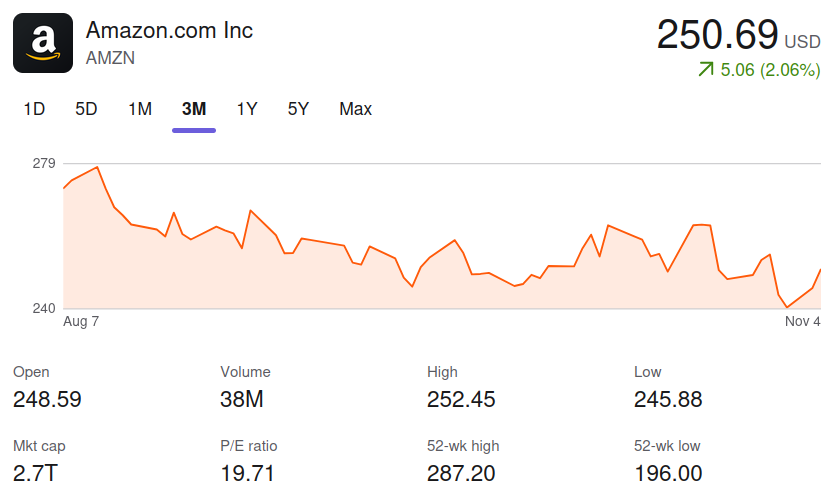
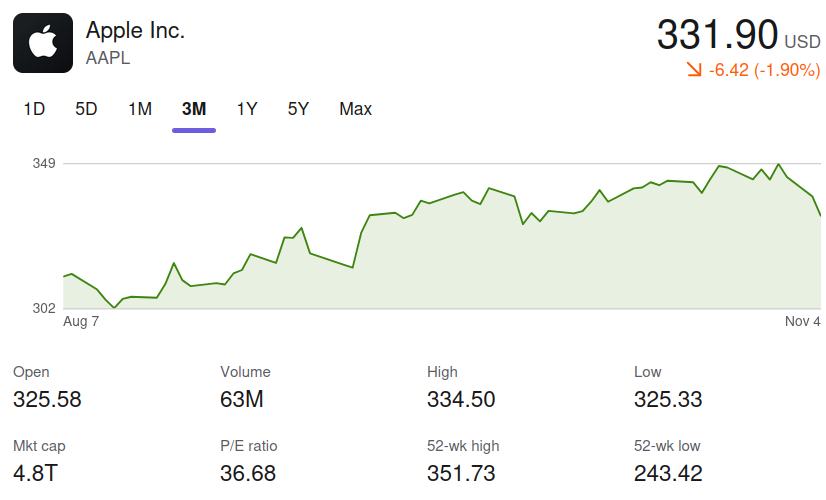
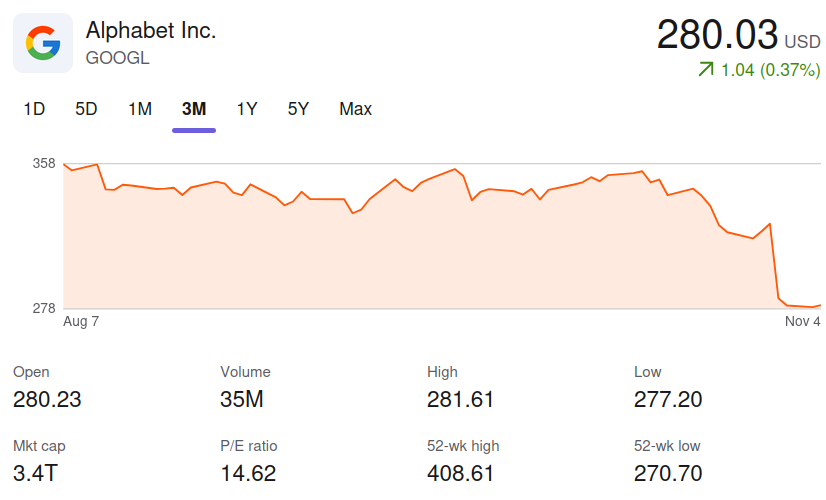
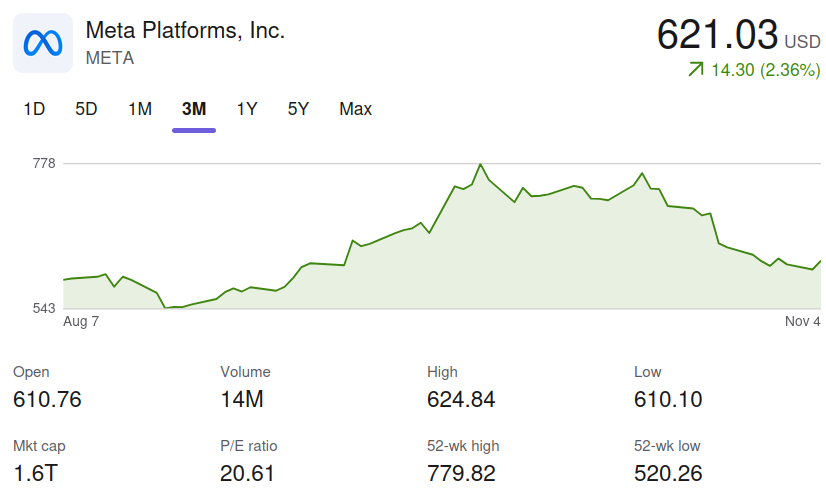
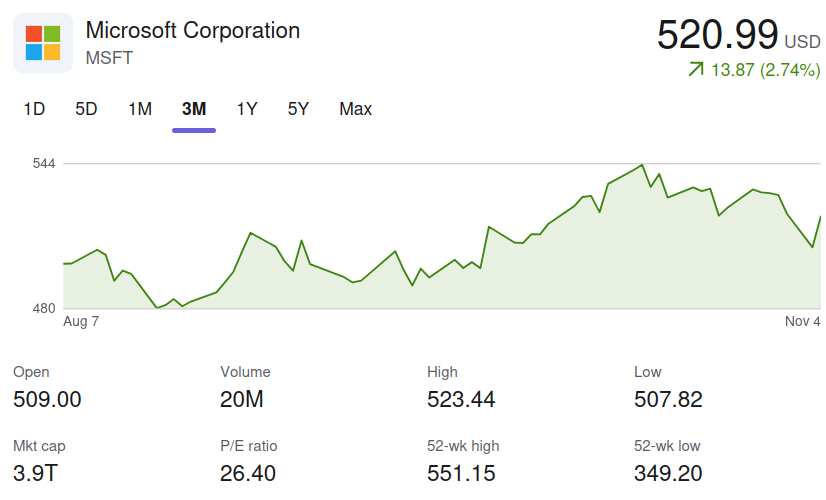
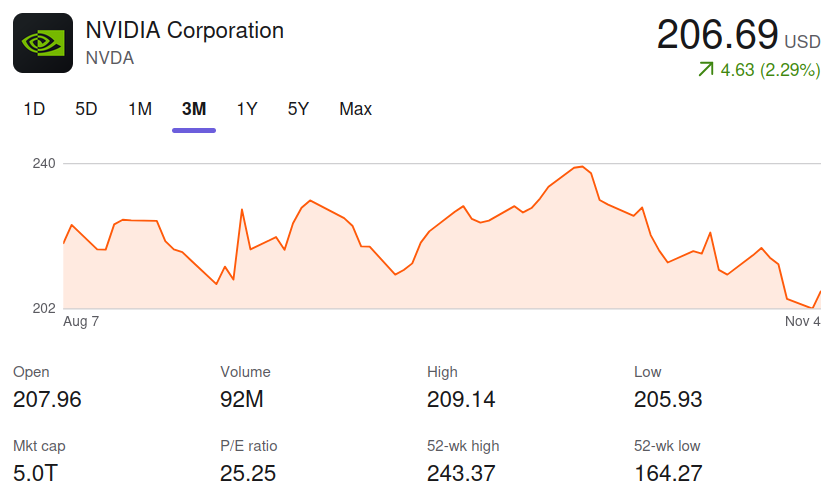
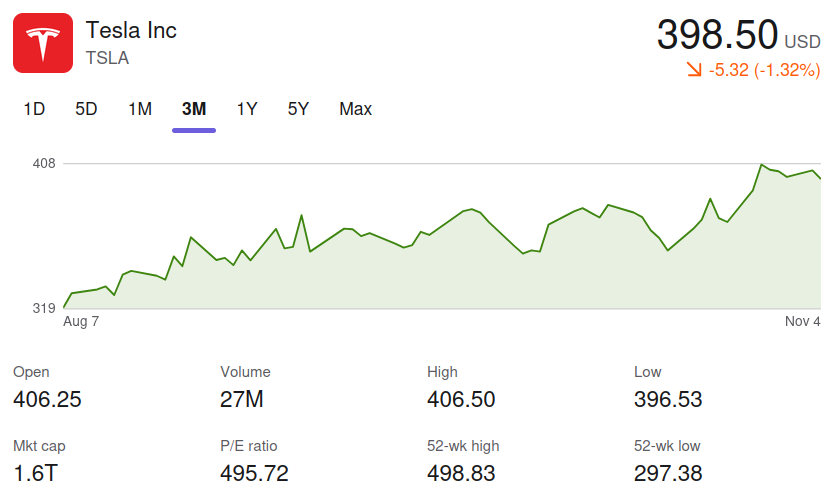
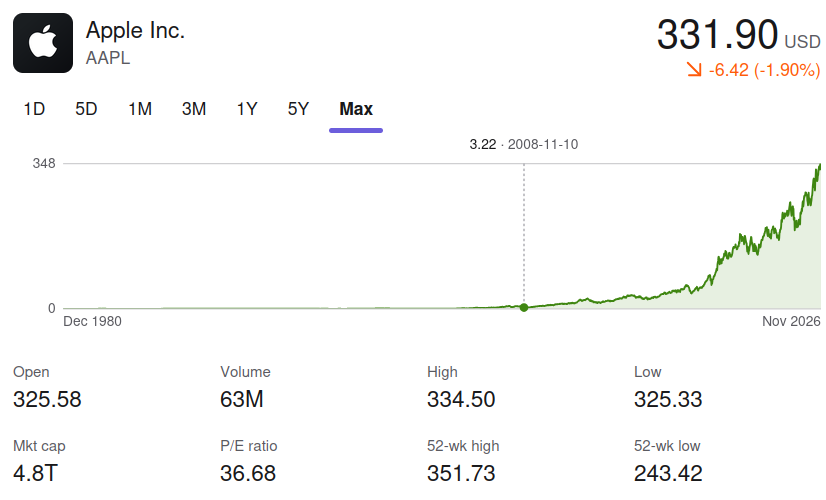
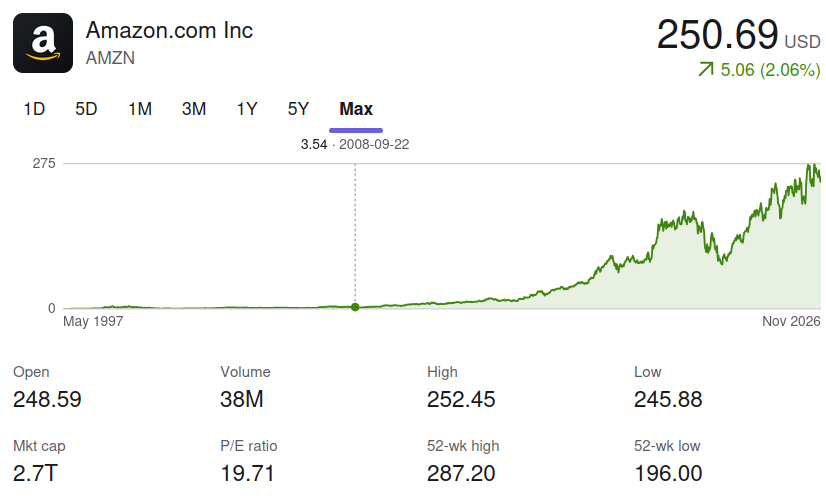
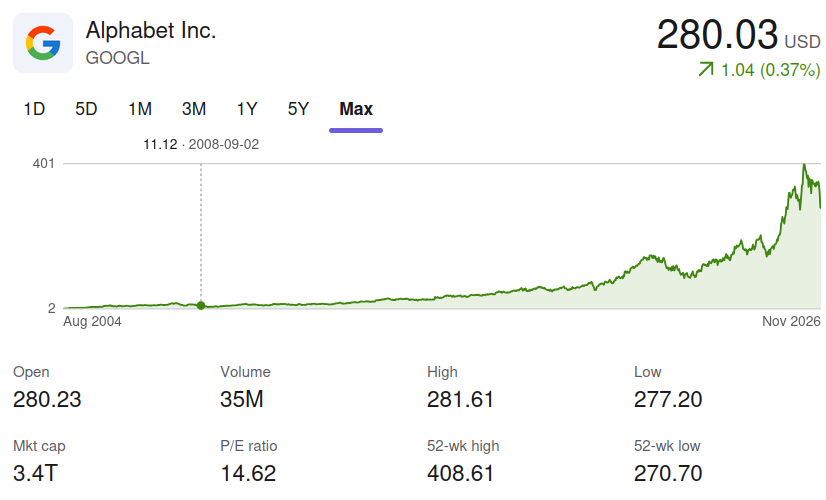
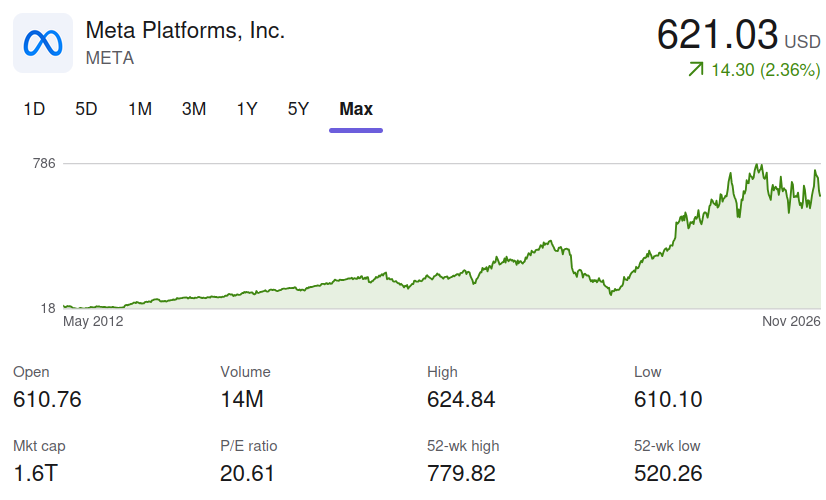
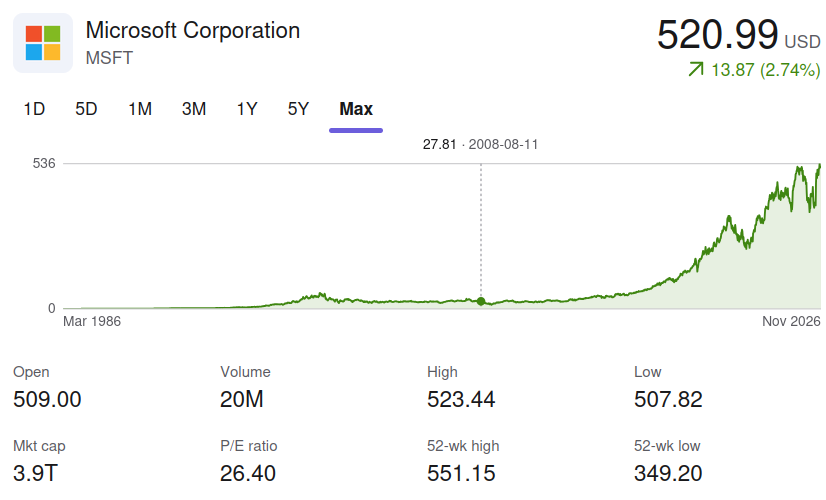
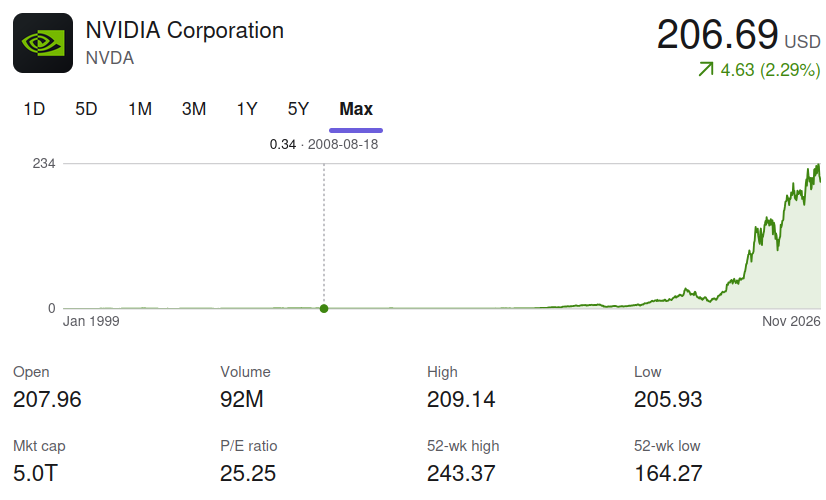
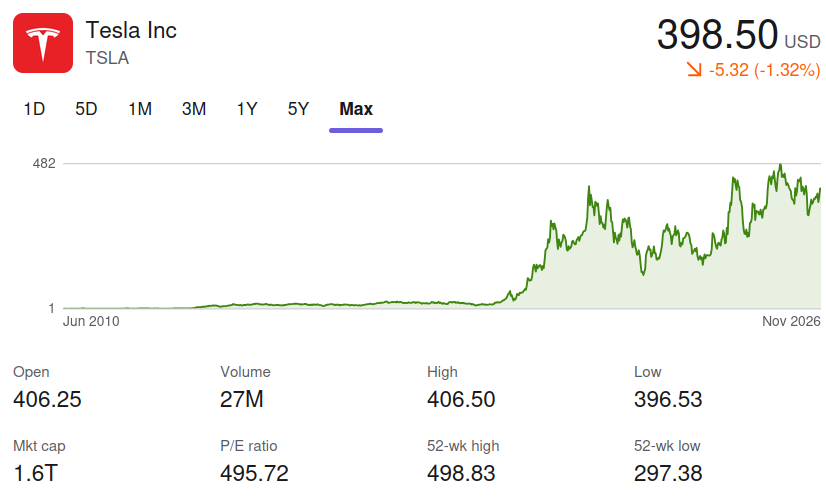
Last year I wrote about the Magnificent 7 stocks and the dependence of the US stock market upon them. At that point they accounted for 31% of the value of the S&P500. Now it is 35%. Let’s have a look at them:
It’s a mixed picture, but Apple, Alphabet (Google), Meta (Facebook) and Nvidia (the one that props them all up) all look like they might be in a little bit of trouble.
But even these have stopped looking like the invincible J-curves of last year. To be sure, Tesla’s progress has always been fairly bumpy, but Meta are now looking like a stock which has moved from J-curve to S-curve. And the next stage would be when investors start to question the current price to earnings ratio of over 20. To do this they tend to use something called a PEG ratio (ie the price to earnings ratio divided by expected growth in earnings per share). The rule of thumb is that, if the PEG ratio is more than 1, it is over-valued. So if Meta are expected to deliver less than 20% growth in earnings per share this year, that would make them a sell. And then a whole different curve shape beckons.
But to return to the charts, notice that I mischievously highlighted 2008 in all of them where the company was going then. 2008 sure looks like the starting gun for most of them.
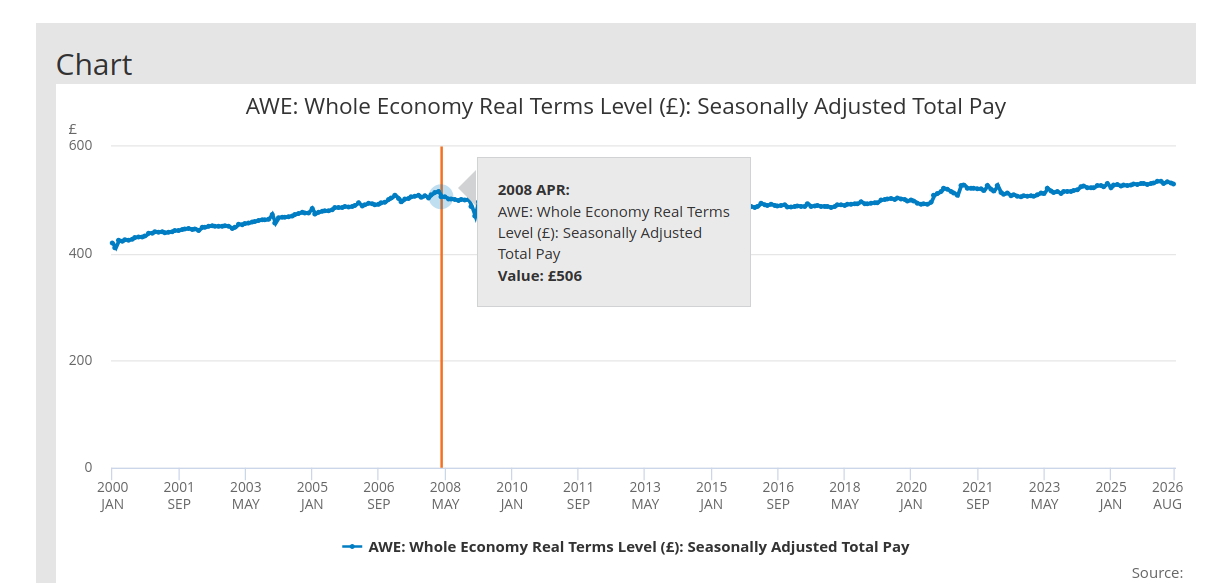
What has economic life been like for most people in the UK over that now nearly 20-year period? Here’s one more graph for you:
My that’s flat, isn’t it? That’s why so many people are feeling flat at the moment. That’s why we’ve had 7 prime ministers (our Magnificent 7) since the Brexit vote in 2016. That’s why we’re squabbling about immigration and the “welfare” budget. That’s why there are riots and looting in France and Germany. We are all just rats in a sack while the Magnificent 7 worry about their J-curves coming to an end.
That situation is no more sustainable than the AI bubble.
Trump has licensed unfettered corporate profiteering and growthmanship. With an added dash of corruption these are a turnoff for the majority of Americans who do not follow the stock market with baited breath. The broligarchs may be popular with a minority of hyped-up stock bros, but in broader terms they are despised.
However he also acknowledges the following:
So, we have been living in a weird and distorted world, with an administration delivering dramatic policies that pull in the opposite direction from voter preferences. If we assume that Congress will now develop a spine and MAGA is lameduck, then the question becomes: how do these tensions unwind and how that unwinding might shape the next few years? After all, the tensions, distortions and contradictions are not confined to the President and his MAGA entourage. Trump’s speedball economy has enlisted powerful interests across the country and the Democratic camp itself has been deeply implicated in both domestic and foreign policy terms.
So a slightly less larcenous politics will be difficult to return to, for everyone, but this is perhaps the necessary first step. Perhaps someone has found a way to nibble a hole in a corner of the sack.
The Magnificent Seven had three sequels. I am sure all of us sincerely hope that I do not need to write any further blogs called Guns of the Magnificent Seven or, even worse, The Magnificent Seven Ride! As David Allen Green has pointed out this lunchtime, the larcenous are very good at stitching sacks closed again. Let’s not let them this time.
10 years ago I was working my way through Cathy O’Neill’s excellent Weapons of Math Destruction, the first really loud warning about the inappropiate application of algorithms, and blogging about it. In the book she set out the case against devolving important decisions to mathematical models without adequate feedback loops. Yes, 10 years ago!
I concluded that post by paraphrasing Robert Oppenheimer’s words about the Manhattan Project:
If mathematical models are to be the dominant regulatory tool of a financial world, and of the consultancies and financial firms competing in that world, then the time will come when mankind will curse the names of the highly paid professionals who followed inappropriate rules rather than exercising their own expert judgement when it mattered.
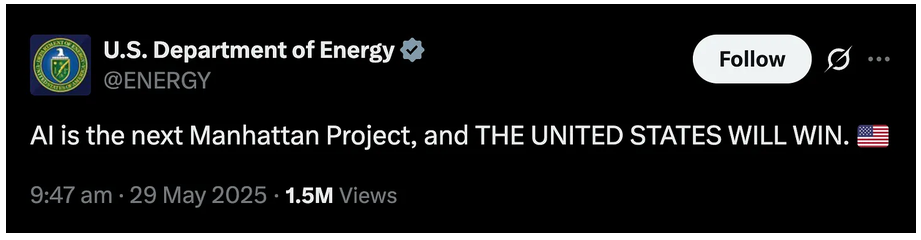
I think that is still a work in progress. Although at least they have made a film about the Manhattan Project in the meantime. And you could say the United States certainly appear to be embracing the analogy:
Meanwhile Cathy O’Neill has done a lot more than just wring her hands about these risks. She has set up her own consultancy (O’Neil Risk Consulting & Algorithmic Auditing or ORCAA) to audit your algorithms for you. As she says:
Whether it’s a hiring algorithm, healthcare AI, predictive scoring system, or generative AI platform, we are here to think about how it could fail, for whom, and what you can do to monitor and mitigate these risks. We are actively developing frameworks and governance approaches to help companies and organizations use algorithms and AI safely – confirming these technologies perform as intended and operate within sensible guardrails. We help our clients realize the transformative benefits of AI, while avoiding discrimination, bias, and other problems.
Their offering includes:
Algorithmic audit, including generative AI, automated decision systems, predictive models, and facial recognition;
Quantitative testing for regulatory compliance;
AI Governance and Risk Management Consultation;
What they call “Cockpit design” – “To make an effective cockpit, you must understand what can go wrong in flight, and include dials/gauges that monitor for those risks. We help build cockpits for your AI systems”; and
Education and Training.
ORCAA have been going for 7 years now, with a range of high profile clients, including AirBnB, Siemens and the City of Amsterdam.
This seems to me a good example of expertise being used in the right way.
A couple of weeks ago I took the IFoA’s AI Manifesto to task for wanting to be on the Red Team rather than the Blue Team, ie the one supposed to be stopping as many AI errors as possible. As I said then:
The Red Team breaks into systems by exploiting a single vulnerability. That is comparatively easy. The Blue Team needs to reassure its clients that it has removed ALL vulnerabilities.
But what if you are not working to protect people from vulnerabilities? What if you are working to protect and accumulate capital instead?
Today I was alerted to the latest article from the IFoA GenAI Working Party, Agent Skills in the Enterprise: Making Actuarial Process Knowledge Reusable. It explains “how an agent skill package can connect reusable instructions with scripts, controlled references, templates, examples and tests”. This will allow organisations to “preserve not only completed models, reports and workpapers, but also the process checks, review decisions and handling of exceptions that produced them using the “agent skill” framework”. As the report puts it:
The problem is not simply that organisations need better prompts. They are preserving the outputs of professional work while leaving much of the procedure that produced them implicit. A completed report records what was concluded. It rarely records every data check, exception, escalation point and review decision needed to reach the conclusion reliably next time.
I can immediately see the motivation. I have been that person trying to replicate a previous valuation result produced by a former colleague I can’t contact, with incomplete data and a-no-longer-supported valuation system which keeps going on the blink. But it was the mention of process knowledge which caught my attention.
I wrote about process knowledge and its importance around a year ago, citing the example of the shrines at Ise Jingu in Japan (which I had learned about from Dan Wang’s Breakneck). This is a now over 1,300 year project to preserve the traditional techniques of building these shrines which involve no nails, just dowels and wood joints. Skills are passed from one generation to the next, there is a tree planting programme which has survived a dozen or more historical eras, pandemics, volcanic eruptions, earthquakes, invasions and oh so many wars over that period. As well as two nuclear bombs.
The important thing is not the ability to build a shrine over 1,300 years later exactly as it was built then of course. It is a proof of concept. It has preserved intricate difficult skills over more than a millenium. And it has involved people, lots and lots of people.
By contrast, the IFoA project has a different, rather shorter term, goal, which is laid out as follows:
This is the first of five articles. The second examines how completed work can become reusable packages. The third introduces SkillOps as the discipline for governing agent skill packages in actuarial work. The fourth considers the consequences for consulting when expertise previously carried through human capital is codified in reusable agent skill packages and becomes intellectual property. The fifth places skills within the wider challenge of continual learning.
It is the fourth article which really bothers me. Once not just the details of a project, but all of the other parts which do not normally get passed on (ie the process knowledge) are captured in this system, it becomes intellectual property, which Cory Doctorow defines as:
any rule, law or policy that allows a company to exert control over its critics, competitors or customers
Up until now, process knowledge has not been given much attention, mainly because it can’t be turned into intellectual property. Process knowledge has always been what remains in the heads of the skilled technicians employed by businesses after everything not nailed down which can be taken ownership of by those businesses has been. Process knowledge has always been the nailed down part. It is the part that has allowed the last vestiges of worker power within most corporations to survive.
Now a group of actuaries think they have come up with a plan to monetize that for the firm as well. To pull up those last remaining nails of worker power.
Think how the IFoA GenAI Working Party would have approached the Ise Jingu shrines.
First you outsource the tree planting programme to a specialist forestry manager. Minimum tender of course: need to get maximum value for money here. Don’t worry about having control over the delivery of timber of just the right type in just the right condition for a unique project. Just leave that to the specialists working on a budget.
Then you sit with the old guys taking you through the various processes involved. Might need some video capture for some of it. Make sure everything they say is captured and then cross-referenced for easier access subsequently. Don’t take too long over it as time is money. Don’t actually feel what it’s like to work with the tools, just note down everything about tool selection. Don’t actually apply the required pressure in the right direction with respect to the grain of the wood, its dryness, the precise cut from the trees selected. Just make sure the video is high enough quality.
I would be surprised if this project survived 20 years. In fact, in view of the fantasy economics of the AI industry, I would be surprised if it lasted even five years if the AI Agents involved in this project relied to any degree on the survival of any of the Magnificent 7.
And this is just to build a shrine out of wood.
These two projects are doing two different things. One is trying to preserve a human activity over a non-trivial period of time. The other is attempting to monetize it so that it can be included in the bottom line for the next quarter. And perhaps to float the idea that your business might be able to dispense with those pesky new employees acquiring process knowledge.
Which brings me to another alarm call. This time from an anonymous group of senior professionals in the UK and European insurance and reinsurance industries called Sounding the Alarm and published in English, French and German. It is not long, so I urge you to read it, but I want to focus on this passage about how the insurance industry is responding to the climate crisis:
Our industry’s strategy is to manage renewals in order to limit our exposure as the physical risk manifests so that premiums are sufficient to cover the rising claims load. This is not a malicious act but a simple response to the commercial realities we are faced with.
We will do this in three ways which many clients are unaware of and governments across Europe are failing to internalise the consequences of:
Firstly, we will reprice our cover. We will simply make policies much more expensive to reflect this elevated physical risk and uncertainty. This will have wider consequences for economic inequality, making it harder for less affluent households to access insurance. It will also increase costs for critical industries such as farming or shipping , creating a significant social and financial burden for government s and, in turn, its taxpayers.
Secondly, we will limit coverage to exclude elevated risks such as wildfires as well as other less predictable risks . The nature of insurance being re – negotiated on a 12 – month basis allows us to do this without friction. Ensuring customers really understand that this is happening is critical.
Thirdly, if there is no way to bring premiums and claims into balance or introduce risk reduction measures we will – for certain geographies and sectors – simply withdraw coverage . This will particularly affect coastal, mountain and flood-prone communities.
This approach is our way of managing our own financial exposure and maintaining profitability at a time of increasing physical risk and increasing uncertainty. Doing so is critical to ensure we can continue to pay claims, therefore fulfilling both our fiduciary duty and our role in society.
This is the flipside of the capitalisation of process knowledge of course. If it can no longer be monetized then ditch it, all the while spouting about “our role in society”. The people on the receiving end will not care whether it is a malicious act or not, it will feel like one.
Both of these stories tell us which side many actuaries are on, and it is the side of capital rather than the side of the people from who it has been extracted. It is not malicious, and it is how many actuaries understand fiduciary duty. To the contract rather than to public interest.
I look back on my own actuarial career. Some time as a scheme actuary where I really felt I was safeguarding the pensions of ordinary people, some time protecting the wealth of already fairly wealthy people from the tax authorities, some time in insurance feeling really quite remote from customers of any kind. And then 10 years helping students into actuarial work. Have I really just been a tool of capital this whole time? Is this why a IFoA sustainability WhatsApp group, which is all about connecting sustainability thought leaders together and raising awareness of the impact of the climate emergency across the finance sector (where I first saw the Sounding the Alarm memo), is so small?
Dan Davies, highlighting Robin Wriggleworth’s new book, A Fabulous Debt: The Epic Story of How Bonds Built the Modern World, wonders whether life insurance actuaries and general insurance actuaries (referred to as casualty actuaries here) have a similar relationship as bond traders and equity traders. It’s a good read. There is even a reference to Craig Turnbull’s magisterial A History of British Actuarial Thought! And this is the conclusion:
Which leads me to the paradox of the title. Reading the histories of actuaries, there seems to be quite a similar needle between the life and non-life insurers; one group place their trust in the higher mathematics, the other deals with heuristics, rules of thumb and vibes. It all comes to a head when you have to draw up the accounts, of course – the big intellectual battle seems to have been the casualty actuaries’ practice of setting reserves depending on the sum of each individual policy, which is really contrary to the spirit of treating risks as draws from a single distribution.
So it makes me think that there is some potential general principle here. Fields of human endeavour where management makes most use of complicated mathematics are likely to be less intrinsically complex and difficult. We use quantitative techniques only when we are content with regarding something as quantifiable.
This feels like a possible explanation. If your acknowledged expertise is in clever mathematics, you are likely to favour techniques which make more things quantifiable and therefore manipulable with clever mathematics. And the more actuaries flood into new fields, the further the quantifying will go.
Capitalism has always been in the business of quantifying things, allocating them to someone (often using considerable violence to do so) and then selling them as property. But late-stage capitalism has a now almost cartoonish obsession with quantifying even things that cannot be easily or successfully quantified, extracting ownership of the thing at the point of quantifying it and then selling it on.
When all the process knowledge has been turned into intellectual property, proprietary knowledge behind paywalls that hide the fact that it doesn’t really work any more, businesses will start to realise that they still have important gaps that are now nearly impossible to fill. There may be a Sounding the Alarm memo about it from anonymous insiders.
Last month the Institute and Faculty of Actuaries (IFoA) launched what it calls its “AI Manifesto“. I thought I would take a look.
The Manifesto is admirably short and to the point. Its pitch can be summarised by this final line of its Introduction and context:
For the benefit of society, we encourage those responsible for developing and deploying AI systems to ensure that there is an actuary in the loop.
Think of it as a massive “Gissa job” plea to those companies currently investing in AI systems. But what sort of jobs are we pleading for?
The idea is that actuaries have been working with models which use machine learning for many years, that we have statistical expertise, are comfortable working with data, used to stress-testing systems and also to looking at the risk appetite of a business as a whole.
I think the first hint that there might be a problem here is when the Manifesto moves onto ethics and the public interest. As it says:
Actuaries help teams balance commercial aims with societal expectations, offering constructive solutions rather than imposing limits.
It is difficult to square this with Anthropic‘s recent IPO filing, where they warn its technology may pose “existential risks to humanity”. I am pretty confident that Society expects not to be put at existential risk. So if Anthropic thinks its technology is that dangerous, there is no balance to be found between commercial aims and societal expectations here. Societal expectations are paramount. And limits will need to be imposed rather than “constructive solutions”.
But, in my view, the main problem here is what “real world” the IFoA feel they are serving. This comes through in the role for “professionalism” they envisage:
Projects with sound validation, honest documentation and clear accountability clear governance more quickly, avoid late-stage rework, and fail in testing rather than in production. Professionalism is what lets an organisation say “yes” to AI with confidence – and protects it from the adverse outcomes that would otherwise force it to say “no”.
This, remember, is in an environment where the latest large language models like Anthropic’s Claude Opus 5.5 or OpenAI’s GPT-6 Astra, are proprietary models where validation, documentation, accountability and governance are all just what they let you see. A framework which allows companies to say yes with misplaced confidence is unlikely to be serving the public interest. And translating a capacity to apply a regulatory model to an insurance company where you have all the data and can make informed judgements about the things that you don’t know (Actuaries are used to working with large, imperfect, transactional datasets subject to audit and regulatory scrutiny. We clarify what data is needed, what quality level is acceptable, and how data should be checked, reconciled and monitored over time) is emphatically not the same as working with a model where you don’t know precisely how it works, cannot accurately predict the errors it will make and do not have enough time to look in all of the places you need to.
Take bias for instance. The Manifesto says:
We examine how a model behaves for different groups and sub-groups, test whether training data is representative of the people the system will affect, and help manage the biases we find responsibly through fairness metrics for predictive models, and output audits and red-teaming for generative systems.
Nita Farahany in the law and policy course documented in her Thinking Freely Substack demonstrates the limits of that bias management in practice, and this is Cory Doctorow on red-teaming (from Red Team Blues):
That’s the problem with blue teaming it—you need to be perfect, while—The red team only has to find a single error
Yes, that’s right, the IFoA haven’t even understood that they are on the Blue Team when it comes to AI errors, ie the one supposed to be stopping as many of them as possible. The Red Team breaks into systems by exploiting a single vulnerability. That is comparatively easy. The Blue Team needs to reassure its clients that it has removed ALL vulnerabilities.
That will be the role of any “actuary in the loop”. And the chances are it won’t be possible. The three examples given by the IFoA are as follows:
A generative AI customer assistant An insurer wants an LLM-based assistant to answer customer queries. An actuary designs the evaluation framework: a curated test set of realistic queries, explicit tolerances for error, escalation rules for high-stakes topics, and live monitoring of answer quality. The project clears internal governance at the first attempt because approvers can see exactly what “good enough” means and how it is evidenced.
A machine-learning decision model A lender deploys an ML model to score applications. An actuary tests behaviour across customer sub-groups, identifies a data artefact that disadvantages one segment, and works with the data science team to correct it. The documentation of that judgement becomes the centrepiece of a constructive conversation with the regulator.
AI risk across an organisation A Chief Risk Officer faces AI adoption in a dozen business units at once. An actuary helps articulate an enterprise AI risk appetite, maps where the organisation depends on the same foundation models, and builds board reporting that distinguishes experimentation from deployment. The organisation accelerates adoption in low-risk areas precisely because it now knows where the high-risk areas are.
None of these examples look unreasonable in isolation, but, to justify the eye-watering expense of this technology, it will need to increase speed and capacity significantly. So, rather than a single generative AI customer assistant, imagine a client relationship management role where a junior actuary or senior student manages 10 times the current expected number of clients at the same time, because the generative AI customer assistant makes that possible?
Will the skills of an actuary versed in the intricacies of Solvency 2 or pensions regulation be so revered by your client that you would be given more than enough time to rubber stamp a system serving 30 or 40 clients? How long do you think you’d need to check the output on all of them properly? I think it unlikely you will be given that long.
This is the risk of becoming a reverse centaur, where you work for the assistant rather than the other way around. And my view is that the actuarial education system is positively encouraging the development of reverse centaurs amongst our current students.
It gets worse. The early evidence suggests that working with AI systems encourages rubber stamping. In one study of AI-generated audits with an auditor in the loop, 150 of the 160 reports were submitted without any changes made by the human. The performance of humans in the loop may also be adversely affected by working with AI systems, leading to “agency decay”:
Agency decay is the gradual erosion of a person’s ability and willingness to observe carefully, think independently, choose deliberately, and act responsibly. It does not arise because AI is inherently harmful. It arises when convenience becomes the default setting for cognition. A tool that first helps us think can begin to think around us, then for us, then without us noticing what has been weakened.
There are lessons to be learned from other professions who have been working for much longer with expert systems. The aviation industry for example. As Craig Bright, Co-Chief Operating Officer at Barclays has posted:
So the test shouldn’t be whether a human appears somewhere on the process map.
It’s whether the system remains understandable, controllable and recoverable when the agent is wrong, uncertain or unavailable.
Safety doesn’t come from leaving a human in the loop.
It comes from designing a system the human can still control.
The IFoA’s position appears contradictory. On the one hand, they clearly don’t believe that AI is as powerful or as dangerous as Anthropic are claiming in order to push up the IPO share price, or I assume they would not be pushing so hard to get an actuary on every team “developing and deploying AI systems”. I think they are right not to believe it, for a number of reasons, but Naomi Alderman’s AI predictions: seven ways you can tell useful thinking from sci-fi fantasies gives probably the most entertaining ones.
On the other hand, if this is just another technology for which the price is going to need to adjust to reality at some point, we need to be very careful as a profession not to be part of the mob urging their clients to adopt it at a faster rate than they would otherwise. Particularly if it is damaging our own professionals in the process.
AI in some form will survive the inevitable crash, but the shape and scope of the wreckage that will be left behind is currently hard to predict. Let’s be careful what we wish for.
Last week I suggested that the period of disruption we have entered would be likely to impact the relationship between society and its institutions and professions, and likened those institutions and professions to the models behind the models we normally focus on. I suggested that this has serious implications for actuarial education, amongst much else.
This week I want to expand a little on what I meant by that.
First, the impact of AI. My view of AI is that I don’t believe most of the claims coming out of OpenAI and Anthropic when noone else gets to see the data and they clearly have a vested interest in playing up the capabilities of their systems. And I certainly don’t believe the fantasy economics the Magnificent 7 are currently indulging in is sustainable (see Ed Zitron’s Hater’s Guide to Circular Financing for more on this). But I do believe that there is a lot of political power with an increasingly out of control stake in it continuing, which makes the quote often attributed to Keynes (“Markets can remain irrational longer than you can remain solvent”, although it may have been A. Garry Shilling in 1999) even more relevant here.
However, what cannot be denied is that the existence of AI is accelerating conversations which we should have been having a long time ago. Last month, MIT issued a report called AI and Education, which turns out to be more a philosophical musing about what we should be trying to achieve in universities, and what expectations we should have of both staff and students. It’s not a long report, but for the time poor amongst you there are two passages from this that I’d like to highlight here.
First, on the expectations we should have of students:
Leaning into learning means creating a new “social contract” between teachers and students. All of us who teach at MIT will need to be prepared to help students understand both that the process of education is necessarily a productive struggle, and that the most important product of their education is not a GPA or a diploma but themselves: their personal growth and intellectual maturity and the development of their own imagination, insight, and judgment.
Instilling these attitudes needs to become a central task for every educator, so that our students know not only what they should learn, but also how they should learn and why learning matters. We need to help them develop metacognitive abilities to think about thinking, to engage in reflective practices, and to enhance their sense of personal agency. This will require both dedication and fresh preparation on the part of instructors.
Remember that social contract idea, because it will be coming up again.
Second, on what kinds of assessments we need to move to in anything we still want to be able to refer to as education:
Rather than simply “AI-proof” current methods of assessment, instructors need to revisit what they really want students to know and devise assessments that foster, or even include, the kind of productive struggle that builds durable understanding and mastery.
We urge instructors to consider forms of assessment that are less vulnerable to AI, and more valuable for learning, such as oral exams, semester portfolios, and out-of-class assignments paired with in-class conversations. This likely means resources such as TAs and class time will become more central to evaluation.
and this:
To match the shift towards assessment methods that aren’t vulnerable to AI, instructors need to increase the role of experiential and project-based learning. To encourage this kind of creative teaching, MIT should support the development of teaching skills and practices for all instructors, and recognize contributions in this domain.
As someone who has already spent some time advocating just such a move in higher education, I feel quite vindicated. But back to that social contract point. I am in a WhatsApp group called Actuarial Change in Education (A C E), where we have been discussing this point for a while, but couldn’t agree what to call it. Culture was one proposal, but I think we all agreed on the MIT point that it should be aiming to ensure:
our students know not only what they should learn, but also how they should learn and why learning matters
One kind of school is about culture, compliance and community. We indoctrinate kids, for better or worse, in what it means to be in this world we’ve built, and how to do it together. We teach them how to be kids, how to be citizens and hopefully, how to be adults.
And the other kind of school is about the content. All the ‘R’s. The software that goes with the operating system we taught in the other school.
The first paragraph is what MIT and my WhatsApp group are referring to. It is the bit which has been assumed we shared in common for too long, but is the most important bit. A shared culture or social contract would allow us to meet and discuss things within a shared set of assumptions about how we can get agreement and take action. It is what has been holding back COPs and peace talks and politics more generally for my whole lifetime. It is also how we decide what we put in the second paragraph, which is necessarily stuff which will be being tweaked constantly and be much more short-term in focus..
The second paragraph is what the Institute and Faculty of Actuaries respond with when you ask them about education (I am only picking on them as this is the one I am most familiar with). Curriculum. Syllabus items. Suggested number of hours study. Past papers to practise for the traditional written exam.
Seth Godin calls this software. It is content. It is largely ephemeral, as the needs of the model we operate in and the tools we are given to do so change all the time. Little of it will survive a decade let alone a career. It does not encourage looking up and wondering if there is a better way. It is full of short-term deadlines and urgency and immediacy. Which tends to get confused with importance.
But the software will never surprise you or deal with situations noone has ever met before. If it is not in the underlying model, it will not turn up in the software. The important education is in the operating system. That is what needs to be reformed.
As I said, there is a WhatsApp group discussing such questions regularly. We are a small group currently, but would welcome new members interested in these questions. If you are, then respond to me in the comments section below or via a LinkedIn message if you are reading it there.
A little more information about A C E is set out below:
What is A C E?
Actuarial Change in Education. A place to discuss where change is needed in how actuarial students learn and the changing landscape they are preparing themselves for. A place to argue about how we teach, and how we get students to care about why they are in education and question the assumptions underlying it. A place to share thoughts and ideas you have had or seen about education, actuarial or otherwise. A place to collaborate with others equally concerned about the future of actuarial education. A place to plan and deliver communications with the wider actuarial community.
What are A C E’s aims?
To have an impact on actuarial education by providing a place for developing actionable ideas about education more generally and how they can be applied to actuarial studies in particular. The hope is that these will then be a useful resource for when the need for alternatives gains a wider acceptance.
Who can join A C E?
Anyone interested in the development of actuarial students.
Two events recently have made me think about the last 55 years in a different way. The first was the last Birmingham Science Fiction Group meeting, which we had dedicated to a 55 year anniversary celebration for the group (the 50th anniversary having been pandemicked). We had a cake, illustrated by David Hardy’s Stratus Hotel, and we showed a film of interviews from members across the years, again featuring some of David Hardy‘s artwork, with stories about guest speakers from Asimov to Frank Herbert to Iain Banks to Jack Cohen and very frank recollections from our current honorary president, Alastair Reynolds. If you want to see the film, you need to join the Group, which you can easily do by emailing us at contact@brumsfgroup.org.uk. Seeing some of the original organisers talking about some of these meetings like they had just happened made me reflect on how we often attribute significance to things after the event and tend to downplay things happening around us now. Things are both never as good or important as they used to be and, of course, as we prove to ourselves over and over again, they also are.
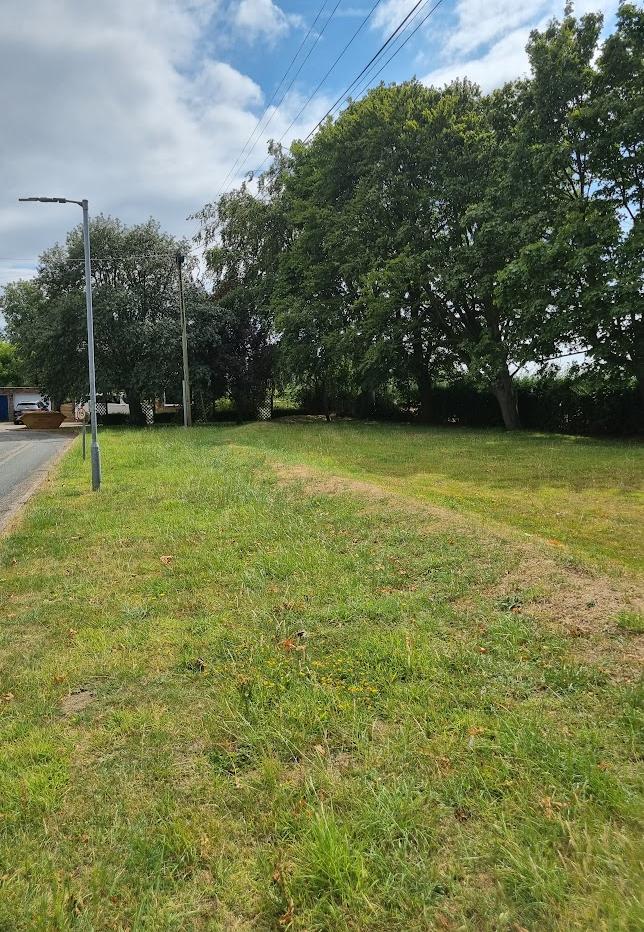
The other event was a visit with my brother and his wife to where we used to live, in the officers’ married quarters of an RAF station in Yorkshire, 55 years ago, when I was eight. Just standing on this patch of grass, with a field of wheat still growing the other side of the fence (to the right), I got a very strong sense of another way of getting from there to here. Obviously there was the one I had taken, with countless house moves, school moves, marriages, careers, children, holidays, illnesses and death and grief and so much joy and laughter in the very fortunate and privileged life I have lived.
But what if I had just stood here and the 55 years had just sped past me instead. My Liverpool football kit would have been a bit tight, with the number seven sewn on the back by my Mum (actually that might have been the following year, when the full magnificence of Kevin Keegan had become apparent). Or, much more spookily, if the eight-year-old just found themselves on the same patch of grass 55 years later in a Wells’ The Time Machine kind of way. It all suddenly felt just as possible and plausible, as if the 55 year old football-and-everything-else pitch was still there within touching distance somehow.
The thing is, I could understand the world of 1971, once I had been reminded of a few things no doubt. A world of cash (just decimalised so no shillings and old pence), phones fixed to houses and telephone boxes, smaller cars filled with leaded petrol, three channels on the black and white TV. I had just driven up there in a car with bodywork comprising mostly plastics, with no spare tyre and no wallet. Just a device known as a mobile which can not only make calls, but send and receive text messages, carry out all my financial transactions and navigate me to my brother’s house. My eight-year-old self would recognise very little about this world beyond the patch of grass he stood on and the field beyond the fence where he had parachuted his mother’s childhood teddy bear.
And this is the terrifying thing about life: we are all that eight-year-old facing the incomprehensible future, and so much of what we spend our time doing is trying to deal with that fear and lack of understanding with often meaningless structures and practices and customs to ward off the sense of being totally out of control. Trump is scary because he appears to have taken a lot of the guard rails off the path we are on, with little sense that he understands what he is doing. AI is scary because it is putting its foot on the accelerator before we have a clear idea of where we are going. Climate change is scary because we no longer look like we are headed where we thought we were.
And we try and stick some grit in the wheels to slow down the disruption to our own little bit of the world, whether to our sense of ourselves, or to how we think life should be lived. And sure we need to question whether we need to change things which are working perfectly well, but often the driver for resisting change is fear of what we don’t know is coming and finding familiar things irresistibly reassuring.
And when we realise that it is not just us with our, certainly in my case, fairly small and unimportant lives (although obviously very important to us!), but also the people who seem to be shaping the world around us that feel these insecurities and uncertainties, the possibility of working together to make it easier to adapt to the very weird future that is coming suddenly doesn’t seem so outlandish after all.
I think this – what we resist, what we create and what we could nurture in the face of this terrifying future – is what I am going to be writing about for the rest of this year, as we all rattle on down the road in the back of someone’s van.
What We Can Know by Ian McEwan is a difficult book to categorise. Some might call it “cli-fi”, as it sets itself in a future significantly altered by human actions and the landscape’s response to those. The Sunday Times appears to think that it might have created a new genre entirely. I think it is best seen as an Oxford novel, even if many of Oxford’s landmarks are submerged for large parts of it. Radiohead even gets a mention. As the petty snobberies and clandestine affairs of academics play out on the much-changed landscape of 2119, earnest academics Tom Metcalfe and Rose Church explore the petty snobberies and clandestine affairs of 2014 and the quest for the long-lost poem from that year. “A Corona for Vivien” certainly feels like a poem which belongs in a past of barn conversions and dinner parties.
For these academics, The Derangement – which is how they refer to the developing crisis mindset between 2015 and 2030 – is just a backdrop to what they regard as the important drama of their lives. It is followed by the first of several climate wars in 2036 involving nuclear weapons, ironically causing a cooling before the Inundation of 2042 causes the deaths of 200 million, with the UK’s population halving and life needing to be eked out on a cluster of small radioactive islands.
I set this out because the book, while occasionally referring to the eeriness of things, carries on with the work obsessions and love lives of its characters pretty much regardless. If What We Can Know is to be believed, academia carries on much as before, with lectures and seminars and essay marking, despite all of this. For humanities departments currently under the cosh despite the absence so far of a nuclear war, this may seem unlikely.
My grumpiness about all this may be partly due to the fact that I am writing this during a series of record breaking heatwaves and unbudgeable heat domes, but I feel like I have had to make more accommodations to the climate – cancellation of plans, a whole new routine at home with the single aim of keeping the thermometer from moving up any further – than McEwan’s characters seem to be doing in their post-not-quite-apocalyptic lives. Whereas one visit to the swimming pool last month was reduced to bobbing about in water along with a couple of dozen others in a manner reminiscent of the wet bulb event at the start of Kim Stanley Robinson’s The Ministry for the Future, McEwan’s only concession to a future world that can still apparently support an academic entirely focused on a 105 year old poem which has never been seen since, seems to be that journeys anywhere are now more difficult and dangerous.
And yet Tom then travels to Snowdonia (where the Bodleian is now housed) fairly easily. And he and Rose then travel to the flooded valleys of the Cotswolds to attempt to retrieve the poem. The only difficult journey described is once they get on to the target island and have to navigate through thick vegetation without satnav (GPS is no more) or even rudimentary hiking skills between the two of them. At one point we are told the internet is on the way out and at another that there is a National Artificial Intelligence which remembers everything you have ever told it.
This book seems as complicit in the “crisis of realism in fiction” as McEwan, via Rose, accuses everything else written between 2015 and 2030 of being. However it is an entertaining Oxford novel, with tense conversations in parked cars and breathtaking egomaniacs everywhere you look.
What we can’t know is what Tom and Rose will make of it in 100 years’ time.
Isaac Newton may or may not have been nutted by an apple. His friend William Stukeley, whose memoir of Newton was the source of the story, states it as follows (spelling and punctuation from Stukeley’s manuscript at the Royal Society):
“why should that apple always descend perpendicularly to the ground,” thought he to him self: occasion’d by the fall of an apple, as he sat in a comtemplative mood: “why should it not go sideways, or upwards? but constantly to the earths centre? assuredly, the reason is, that the earth draws it. there must be a drawing power in matter. & the sum of the drawing power in the matter of the earth must be in the earths center, not in any side of the earth. therefore dos this apple fall perpendicularly, or toward the center. if matter thus draws matter; it must be in proportion of its quantity. therefore the apple draws the earth, as well as the earth draws the apple.”
However there may be stronger grounds for believing that Newton nutted English mathematics and, as a result, the actuarial profession.
I thought all this to myself, occasion’d by participation in the Actuarial Teachers and Researchers Conference (ATRC) this week. It was great. There were lots of interesting talks, and people were very engaged and respectful in how they discussed them. There was a lot of expertise in the room about both education and actuarial practice and theory. It felt like it was a room that could take on difficult topics and make progress in tackling them.
There were several calls for the need to change assessment, one of them by me, whether due to large student cohorts and the difficulties of engaging them, or the ease with which AI can duplicate examination solutions or because the credentials provided by those assessments seem increasingly irrelevant to the actual actionable skills, knowledge and experience required to operate successfully as an actuary. And there was an equally robust response from the Institute and Faculty of Actuaries (IFoA) to the effect that assessments would not be changing significantly in the latest changes due to come in by 2029.
My favourite presentation was by Angus Macdonald, about his recent short paper on Newton, Leibniz and Actuarial Science. It conjectures that the argument between Leibniz and Newton over who invented calculus resulted in the stagnation of mathematics in English universities and meant that actuaries needing to gain respectability for their advice were forced to create a professional body (in company with architects, accountants and engineers) rather than rely on universities to develop actuarial thinking as happened in continental Europe. This stagnation (Macdonald quoted G.H.Hardy, talking about the Cambridge mathematics exams, saying that they had “. . . effectively ruined serious mathematics in England for a hundred years”) was felt across the whole Anglosphere, with attempts to create institutions with equal status to the traditional universities leading to the establishment of business schools in the USA in the late 19th and early 20th centuries.
This explained a lot for me. The suspicion of our actuarial courses amongst some of our mathematics colleagues at times at Leicester. The occasionally uneasy relationship between the IFoA and the accredited universities where students can gain exemptions from their exams. The horror from some at the very idea that an actuary might qualify as a result of university courses, like they can in the Netherlands, for instance. ATRC seemed the appropriate place to explore these ideas.
Angus Macdonald considers that the Newtonian and Leibnizian branches have nearly rejoined, but I feel that our actuarial education system still suffers from the long shadow cast by these two 17th century gentlemen and their personal enmity. The ferocity with which some within the profession opposed what they saw as a threat to the popularity of the fellowship qualification posed by the new chartered actuary designation was hard to explain when the number of practising certificates issued for chief actuaries, pension scheme actuaries, etc was only around 1,100 (out of over 17,000 fellows), but if the whole profession originated from a highly developed form of status anxiety compared to academics, it becomes much easier to understand. As they say, the apple doesn’t fall far from the tree.
Now, nearly 180 years on from this “unstoppable” “rush to respectabilize” (according to Jeremy Paxman) I think it is legitimate to ask:
Why does the IFoA still insist on detailed accreditation of individual university courses on basic mathematics, statistics and business economics? Do they not trust them to teach them right? Do they think that there is something better about learning these universal subjects via a bespoke course created by a tiny professional body with 34,000 members globally?
Why are they so concerned about what assessment methods the universities use? Do they consider that they have more educational expertise on this than some of the leading universities in the world?
I have written previously about the changes in assessment I think are necessary and floated some ideas about where actuarial education might sit to accommodate these. My view was that the IFoA, faced with the need to innovate at all levels of its education system at a time of great uncertainty, might wish to get out of the foundational mathematics and business education tuition of the core principles subjects and leave this to the university system, in a truly Leibnizian way.
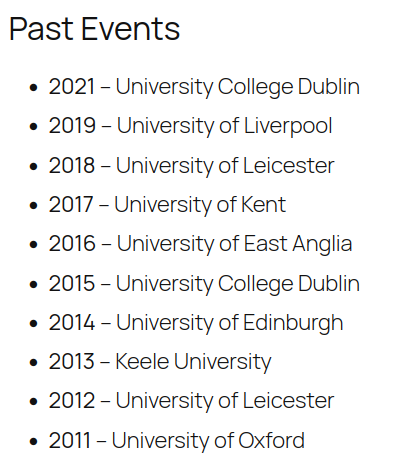
In actuarial science, the list of UK universities offering accredited courses has not changed for some time, and it is a small group within the university system. These courses must be seen as vulnerable. I don’t think it is a coincidence that it is so hard to persuade one of this tiny band to run the ATRC. This week’s was the first since 2021 and the list of past hosts is not very long:
The IFoA needs to ask itself what it would do if there were some high profile closures of actuarial courses and whether perhaps it might be time to protect the core mathematical education arrangements for actuaries through a broad brush accreditation of a wider range of courses, rather than the very detailed accreditation process it currently carries out on core principles subjects.
I also doubt that it has the capacity on its own to significantly restructure its assessments beyond the objective based assessments it has developed to work within its proctored environment.
The core practice and specialist subjects leading to fellowship are the areas where actuaries have, rightly, the strongest views about content and assessment structures. It surely makes sense that the expertise within the profession and the university system are pooled in a joint endeavour rather than risking both failing independently.
In contrast to Newton, who had quite a temper, Leibniz was famously parodied by Voltaire in his Dr Pangloss character in Candide who believed that “All is for the best in this best of all possible worlds.”
Let’s not be too Panglossian about the current state of actuarial education.
As I discussed in How Not To Be A Reverse-Centaur (Cory Doctorow defines a reverse-centaur as “a machine that is assisted by a human being, who is expected to work at the machine’s pace”) our actuarial education system needs to change. This has been true for some time, but the development of AI systems has both demonstrated why more clearly and accelerated the timeframes over which action is needed. As I said in December last year:
A large part of the education of the future will need to be about equipping us all to understand what we now have access to and when and how to access it. We will all have different things we are interested in, or end up involved with and needing to be educated about. It will be up to each of us to decide which things are worth the difficulty of learning, but to make those decisions we will need education that can support the development of judgement.
For education institutions, the question will be what is not worth the difficulty of learning? Credentialising based on now relatively meaningless assessment methods will not cut it. This is where the confrontation with employers and politicians is likely to come. Essential skills and their related knowledge will be better developed and assessed via more open-ended project work and online assessment of it to check understanding. These will need to become the norm, with written examinations becoming less and less prevalent. Not because of fear of cheating and plagiarism, but because an outcome which can be replicated that easily by AI is not worth assessing in the first place.
Suppose you were to ask someone who had never seen our academic system that, in order to assess whether someone else we wanted them to employ in their organisation would do a good job for them, we would:
Award marks for what has been written in answer to academic questions about what the students can remember unaided about the content of their lecture courses and reading lists with a biro on a pad of paper perched precariously on a tiny wooden table surrounded by hundreds of other similar scribblers, for a set period of time as minders wandered the floors like Victorian factory owners.
These marks would be based on marking criteria they would never see.
We would then get together in a secret huddle for a couple of months to mark all these scripts, check them and “moderate” them to check they were in line with the previous years’ exercises.
Then out would come the answer (like the Answer of 42 to the Ultimate Question of Life, the Universe and Everything in Douglas Adams’ The Hitchhikers Guide To The Galaxy).
Imagine another world where the kinds of things employers routinely do when trying to decide whether to take on someone as a new member of their organisation are routinely part of their assessments at university, eg:
Watch them operating in groups working on a task.
Ask them to describe how they would go about tackling a particular problem.
Get them to show they understand the implications of a piece of work they have carried out and can explain what assumptions it is based on and can justify them.
With assessments of performance which are not opaque academic exercises but descriptions of performance made as the tasks are being carried out evidenced by video if necessary. In other words, transparent enough to whoever might want to work with these students next to eliminate the gap between their credentials and and their actual actionable skills, knowledge and experience.
Assessing in this way will be highly demanding, for both the students and the assessors, but it means the final assessment is done with the student present and, with careful probing from the assessors, who will obviously need to have done a close reading of the project work beforehand, confidence will be high about the abilities demonstrated by the process. And it removes the need for all the time currently spent on the Victorian factory owner process – imagine what could be done if the whole of May, June and July wasn’t spent marking scripts!
A move like this will significantly change what is taught. There will be no point presenting lots of information in ways which make retention easier for students (the so-called bookwork” questions currently in most exams). This makes sense when you think about how much of the content of your courses is accessible to you now, even on a vocational course like actuarial science, as opposed to skills developed. Instead the focus will be more on conversations with students for the purpose of developing their understanding of a meaty topic and the problems to be solved within it. Explorations of these will form the projects students will be spending most of their time working on. Checking understanding and making sure students are working within frameworks they understand and can talk about will be the main teaching activity, with opportunities to practise these throughout the year. In other words, showing the ability to apply what they have understood and demonstrate the ability to reflect, make judgements and show higher levels of understanding as a result. An ability they can then apply to new problems and situations.
And notice something else about how these alternative credentials are generated? They are all social activities: from operating in groups, to presenting a piece of work to a group of assessors. Even the project work is developed through group sessions alongside individual work. If you want to develop people who can spot the gaps between models and reality you need to do it in groups, where people can test their perspectives against each other.
Compare this to the current solitary exam preparation, peppered with “revision” lectures, exam sitting and exam marking processes which comprise the predominant activities in universities between March and July each year. We are currently being funneled into an ever more solitary professional practice around LLMs. It has become quite accepted for people to do all of their thinking on a subject closeted with perhaps one, two or three LLMs but no other people and then share their analysis with an expectation that other people should read the output. Developing the skills to do these analyses will obviously be necessary, but they will never be the most important skills people learn.
Treating each other like walking databases is never going to make you new friends or influence people. However the skills you develop via an alternative more social education will.
There are examples of this approach already happening, with employers involved in the design of assessments in some cases and universities using the flexibility they have to restructure and redesign courses. But the dominant assessment system of formal exams is keeping much of this activity at the margins at the moment.
If it were to become the dominant assessment, it would also mean that larger areas of the curriculum could be examined, as the focus would not be on retention of large bodies of content but the ability to use the content to solve problems. So, perhaps, after a first year levelling up students’ ability and experience of mathematics and statistics, year 2 would have an actuarial statistics module (currently CS1/CS2) and an actuarial mathematics module (currently CM1/CM2), both dissertation based and vivaed. Then in the third year they would tackle an economics module and a business modules (currently CB1 and CB3). Perhaps in the final year of a four year MAct they would tackle a modelling and communication module (CP2/CP3) and either CP1 actuarial practice module would be offered or a professional skills module.
This would be more of a driving test style of assessment, with students working with supervisors on the comments from assessors on the original dissertations and presentations until they were up to the required standard. Students unable to make the standard after an additional year would be offered a move to a non-accredited course. The current funding model for higher education will need to change: loading students with £10,000 more debt every time they add to the nation’s skills bank with another year wrestling with these difficult skills to master was never a clever strategy, but this structure would make it even clearer how self defeating it is. If economists are accepting that the labour market no longer allocates resources effectively and are considering either a universal basic income or universal basic services, then logically university funding should follow suit.
The implications for the actuarial profession will be even more challenging. I question whether the Institute and Faculty of Actuaries will continue to consider it worth the effort and expense of reconfiguring their entire approach to exam setting, syllabus maintenance, marking, online proctoring, etc for subjects routinely taught throughout the university system for a a variety of purposes, ie the current core principles subjects of mathematics, statistics and business studies.
Whether they retain their own capacity to assess the core practice subjects is a more open question (CP1 Actuarial Practice, I imagine, will be seen as sufficiently specialist to keep in house, with perhaps a few universities, as now, accredited to run courses which can earn this qualification, however CP2 Modelling and CP3 Communications are not nearly as specialised now as they seemed when they were first introduced). I would also move the new core economics module recommended by the IFoA Economics Review Group I chaired in 2022 to replace the current CB2 module into the core practice section, as it would be more of a critical thinking module about the economic ideas necessary to underpin good actuarial work than the technical how-to subjects in core principles.
The specialist stage of the SP and SA subjects and the whole continuing education and additional certification options I would confidently expect the profession to retain, review and adapt as needed to reflect new challenges in members’ working lives. However, if CP1 is all that is needed post graduation to get to Chartered Actuary and CP1, two SP subjects and a SA subject gets you to Fellow, then suddenly time to qualification becomes much more predictable for students and their employers alike.
The risks to employers of taking on students would therefore be reduced, but also the rewards to taking them on will be much more transparent. The students we will be developing will have collapsed the gap between their credentials and their actual actionable skills, knowledge and experience. They will have:
Great team working skills;
Very highly developed presentation skills, both in writing and speech;
Strong IT skills and comfort working with data; and
Clarity about why they are in an organisation and a drive to use their skills to solve problems.
Epistemic rigour. They will be more likely to spot when a system or model is over-confident given the evidence, after an intense experience of interrogating models and evaluating evidence in their courses.
Synthesis. They will be able to integrate different perspectives into an overall understanding, through dissertation development, defending a position, understanding weaknesses in a position and adjusting accordingly.
Judgement. They will have been asked to make many judgements in their work and had to defend them in discussions with their supervisors and fellow students. Unconvincing opinions, not backed by evidence, will not pass muster.
Cognitive sovereignty. Students will have to take their own stand on their work, after all of the challenge and argument. Independence of thought is the hard-earned outcome here.
And then they will have a fighting chance of being centaurs in the world awaiting them, masters of the technology and opportunities available, rather than the reverse-centaurs that our education system is currently, and inadvertently, preparing them to be.
It all started for me in May 2017, with the challenge from Daniel and Richard Susskind in their book “The Future of the Professions”, which set out two possible futures for the professions. Either:
They carry on much as they have since the mid 19th century, but with the use of technology to streamline and optimise the way they work; or
Increasingly capable machines will displace the work of current professionals.
Their research suggested that, while these two futures would exist in parallel for some time, in the long run the second future would dominate. The actuarial profession was going to be particularly vulnerable. As the Susskinds wrote:
Accountants and consultants, for example, are particularly effective at encroaching on the business of lawyers and actuaries.
I stood in the Institute and Faculty of Actuaries Council elections that month, on a platform saying that we needed to urgently respond to this challenge. I didn’t get elected.
However, at the University of Leicester we pursued a curriculum transformation programme in response to this challenge aimed at developing actuaries of the future who had:
Highly developed presentation skills, both in writing and in speech
Great team working skills
Strong IT skills – comfortable with working with data
Clarity about why they are there and the desire to use their skills to solve problems
The 2017 post also talked about emerging trends which had hardly started at all yet:
The end of reserved roles for actuaries
Different ways of communicating advice
Online self-help for users of actuarial advice
The advance of roboactuaries and their assistants
A paper called 2036: An actuarial odyssey with AI written for the Society of Actuaries in July 2016 by Dodzi Attimu and Bryon Robidoux discussed the possibilities for robo actuaries and robo actuarial analysts.
They estimated that robo actuarial analysts would be with us in 5-10 years and would provide:
A system that has limited cognitive abilities but can undertake specialized activities, e.g. perform the heavy lifting in model building (once the specification/configuration is created), perform portfolio optimization, generate reports including narratives (e.g. memos) based on data analysis, etc.
Whereas a robo actuary was more like 15-20 years away and which they also helpfully described:
We mean a software system that can more or less autonomously perform the following activities: develop products, set assumptions, build models based on product and general risk specifications, develop and recommend investment and hedging strategies, generate memos to senior management, etc.
Then, in 2018, there was the whole Bullshit Jobs argument posed by the late David Graeber, discussing Keynes’ prediction in 1930 that:
In quite a few years – in our own lifetimes I mean – we may be able to perform all the operations of agriculture, mining, and manufacture with a quarter of the human effort to which we have been accustomed.
Graeber, in Bullshit Jobs, pointed out that this never happened, despite pretty much all of the technological developments and income increases which Keynes predicted. He suggested that the future which the Susskinds were predicting is already happening in terms of needing fewer people to fill the meaningful roles within organisations but that, rather than employing fewer people, we are either creating “bullshit” jobs which even the people doing them can see no point to or bullshitizing existing roles for which the meaningful need has passed. It was as if the organisations themselves have attempted to maintain the outward appearance of the same structures by disguising the hollowing out of so many of their functions with simulated business.
Why? One of the reasons he thought the situation had been allowed to develop was that noone believed that capitalism could produce such an outcome. Graeber gave the example of the creation of Obamacare, where Barack Obama “bucked the preferences of the electorate and insisted on maintaining a private, for-profit health insurance system in America” in order to protect jobs in health insurance.
Then we had the pandemic, and the painful return to work which found that people were not necessarily keen to return to populating those office empires, preferring to work remotely. Some of the attempts by the captains of industry to get them back were a little desperate.
Now nine or ten years on from the initial challenge, we are deluged in articles about how AI is impacting different areas of actuarial work, whether it is already replacing graduate roles and what actuarial students need to do to make themselves employable. And now the blinkers also seem to have come off about capitalism not producing the need for fewer jobs.
Historically, accountancy firms have typically had a pyramid structure – wide base, heavy graduate recruitment. Firms are now starting to talk about a ‘diamond model’ with a wide middle tier of management because, ultimately, AI is not sophisticated enough yet to make those judgment calls.
But hang on a moment. Now there is something called an “AI boomerang”. Sam Altman of Open AI and Dario Amodei of Anthropic have both been backtracking on their predictions of job lay offs due to AI. As the Gold and Geopolitics Substack puts it:
Two-thirds of the companies that ran AI-driven layoffs last year are now rehiring. One in three spent more on the rehiring than they saved on the original cuts. Robert Half calls them “AI boomerangs” – which is the name a consultant invents when there’s a market in unwinding what the last consultant sold you.
The last few years of AI-generated headlines (in both senses of the phrase) have been quite the rollercoaster.
I do not want to add to the deluge, as currently you would need a LLM summarising reports for you 24/7 just to keep up with it as it is.
And there are good reasons for not rushing to judgement on this. It is only six weeks ago that the Bank of England’s Head of Financial Stability warned that global stock markets are overvalued. As she said:
The thing that really keeps me awake at night is the likelihood of a number of risks crystallising at the same time – a major macroeconomic shock, confidence in private credit goes, AI and other risky valuations readjust – what happens in that environment and are we prepared for it?
Since then, the economics of the major AI players has only got more bonkers. In this environment, there is considerable uncertainty about what students should be learning to prepare them for the world they will need to rebuild from the rubble of the current one.
Daniel Susskind reckons a “no regret” strategy for education would focus on the basics, which he describes as literacy, numeracy and critical thinking, and the critical use of AI. Carlo Iacono talks about the work which will always be hard to automate as follows:
The work that depends on reading a room. The work that relies on institutional memory. The work where the important fact is not in the document. The work where the answer is political, ethical or relational as much as technical. The work where being right is not enough, because someone has to be accountable for the consequences.
But you have to get into the organisation first before you can develop much of this. I remain reasonably comfortable with our prescription from 2017 in terms of broadly what the curriculum should be trying to achieve. Curriculum changes take time and, tempting though it is to pile into syllabus changes aimed at incorporating the latest cutting edge technological developments, the likelihood is that you will be arriving at the wrong fire. As a social media post this week put it:
The danger is that, as Agentic AI in particular looks so much like the predictions of 2016, we declare it the new messiah and bet everything on this being the future. I certainly think that 2036 will look very different to now, but I am not convinced that we have the shape of it yet. This may just be another bullshit alternative, waiting for the next crisis to mutate into something else.
What we can say with certainty is that the future for early professionals is as uncertain as any of us can remember. And, in my view, the best way to support our young people starting their professional lives (or whatever is going to replace professional lives) is to make the value they add much clearer to anyone who might want to work with them in the future.
Future education systems are going to need to help their graduates demonstrate their value in ways they haven’t historically needed to. AI has not brought new problems, it has accelerated existing ones. And the gap between actual actionable skills, knowledge and experience and the credentials which are supposed to represent them is the key one I believe as far as those graduates are concerned.
Because currently the companies who might want to take them on have to guess what they can do to a large extent. What does a 1st mean? A 2.1? Do the differences matter to their employer? Should they interrogate the details of student courses? How would they incorporate that into a manageable recruitment process? Some people see a future of AI generated applications by the thousand per student doing battle with AI powered triage systems operated by potential employers.
This is already an issue in academia. The conclusions of one academic paper on submissions to one major academic journal were stark:
Submission volume has risen 42% since the late 2022 release of ChatGPT, while writing quality has declined. The rise in AI-generated writing accounts for nearly all of these trends.
On the other hand, researchers complain about the increasing use of AI peer review to try and cope with these increased volumes, and some have tried to game the LLMs they believe they are dealing with.
I think we can do better than this in actuarial teaching and learning.