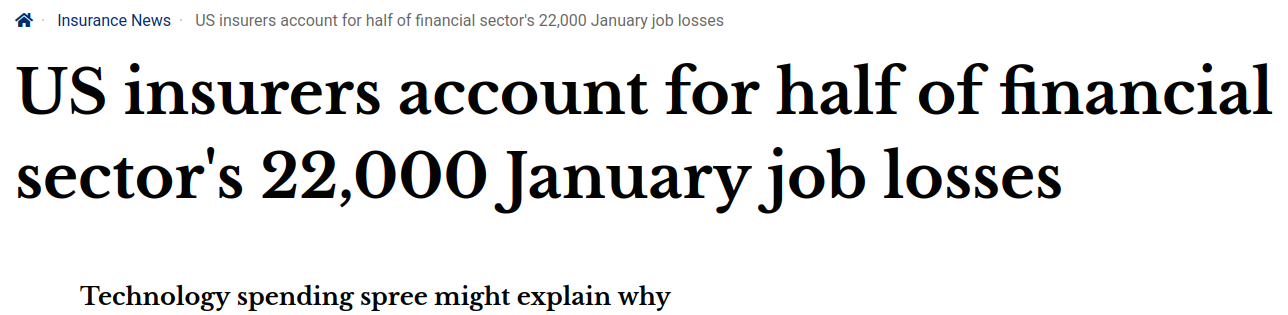
We shall not cease from exploration
And the end of all our exploring
Will be to arrive where we started
And know the place for the first time.

T.S. Eliot – Four Quartets

I feel like I am having a bit of a T.S. Eliot week. I have been writing about the OBR since the beginning of this blog in 2013, with their repeated failures as a forecaster forming the banner for the blog for many years.

What has brought me back to the OBR, as if for the first time, is recalling during the recent Funding the Future conference the words of the very good and wise friend of mine who was there with me. I had invited him to talk to one of my undergraduate groups at the University of Leicester during a professional skills session a few years ago. We were looking at past disciplinary cases of the Institute and Faculty of Actuaries and discussing what the actuaries involved could have done better.

In one of the case studies we considered, an actuary had produced a quarterly reserving report for a company, estimating the reserves on a ‘high’ basis of £74.5 million, a ‘low’ basis of £36.9 million and a ‘best’ basis of £52.1 million. The company then produced financial statements for the year, approved by the board of which he was a part, containing a reserve figure of £15.5 million. My friend told the students that the way to challenge in a situation like this is not to focus on the numbers, but instead see that each different number reflects a different story being told. So you need to look at what the story would need to be for the £15.5 million to be an appropriate figure and take issue with the things that don’t make sense within that story.

It was great advice then and still is, and it is definitely the way to look at the OBR I think. We find a story unsatisfactory if the characters are shallow, do not behave in a credible way, and the plot oversimplifies a much richer situation (something which every story must do to some extent to be manageable to the reader) in a deeply unsatisfying way.

Several other commentators have talked about the inability of the OBR to forecast anything (including me) – this is the equivalent of insufficiently fleshed out characters behaving in unbelievable ways. Richard Murphy, for instance, pointed out how ridiculous the proposed character plotline for inflation was at the last budget:
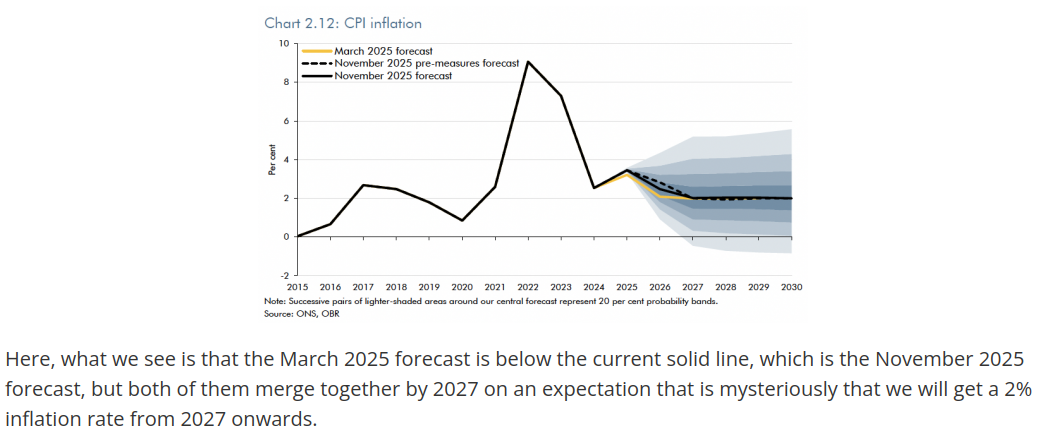
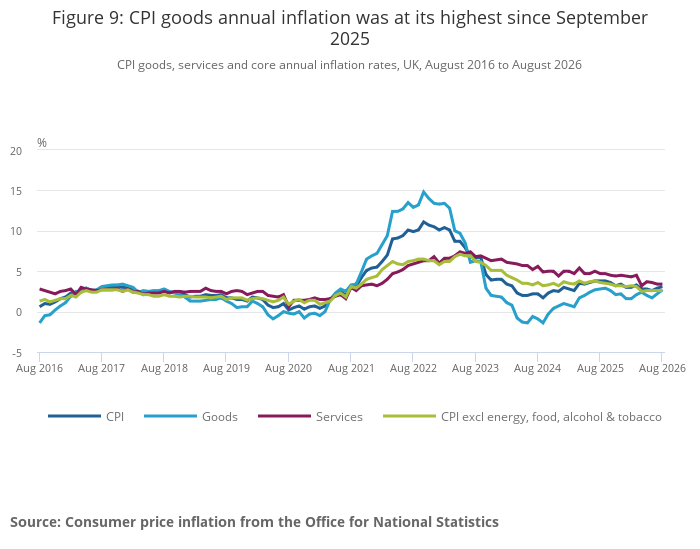
Whereas in fact of course the downward trajectory predicted at the last budget didn’t look remotely likely even then. The Consumer Prices Index (CPI) rose by 3.1% in the 12 months to August 2026, up from 2.9% the previous month.

However it is Dan Davies’ recent couple of Substack posts (one and two) which get to the heart of the problem in my view. Dan Davies’ contention is that it is the plot oversimplification which is the main problem here. As he says:

The system we have set up only seems to be able to communicate two states though – the signal is either “COMPLIANT – WAR CHEST” or “NONCOMPLIANT – BLACK HOLE”. It would be a significant improvement even for the OBR to add some measure of urgency or non-urgency to its press release – a sentence like “this surplus is well within the forecast error, however, so it should not be used to justify a change in policy”.

But, in his view, it is even worse than that:

In general, most things which a government spends money on will tend to have effects on the economy which go well beyond the five year forecast. The OBR uses an information set which contains only a small and quite arbitrary subset of government decisions – it is, literally, not capable of representing the system it is meant to control at an acceptable level of accuracy.

The justification for ignoring the future consequences of current spending seems to be no more sophisticated than what we pejoratively call “Treasury Brain” – the belief that a) spending departments always claim that their budget should be seen as an investment, b) that they systematically overestimate the long term benefits of current costs and c) that the best solution to a) and b) is to completely ignore any future benefits from investment or future costs caused by noninvestment. It’s just not good enough.

It is this dog’s breakfast that apparently tells us whether we are on track to meet the plotline the government has set for itself. Its three fiscal rules:

Rule 1. The current budget should be on course to be in balance or surplus by 2029/30 (‘stability rule’);

Rule 2. Net financial debt should fall as a share of the economy in 2029/30 (‘investment rule’); and

Rule 3. Some types of welfare spending must remain below a pre-specified level (the ‘welfare cap’).

And if that gruesome threesome doesn’t set your heart racing about the country’s future story, you are not alone. Because the people banging on about fiscal space will always push for governments to spend less, regardless of the circumstances. For instance, at the height of the pandemic in December 2020, Moody’s were saying this (with excess deaths already estimated at over 30,000 in the UK by Public Health England at that point):

However, compared to the government’s March budget (that was quickly overtaken by events), there are some initial signs that fiscal policy outside of investment is likely to be less expansive than previously announced. What remains unclear is whether this ambition will be able to withstand the political pressures that seem to be inevitable given the government’s previous commitments. Even before the Spending Review, longer-term spending commitments for health, education, and defence had already been announced. Together, these three areas account for around 60% of total expenditure.

One of the themes from the Funding the Future conference was, to quote from Educating Rita:

“There must be better songs to sing than this”.

I agree. One possibility is proposed by the New Economics Foundation, who suggest categorising policies by their level of multiplier effect (ie how much economic activity is increased by an increase in spending) and replacing fiscal rules with a “fiscal referee” who can make a more holistic judgement addressing many of the omissions Dan Davies complains about. This would then lead to a discussion rather than the compliant/non-compliant cliff edge we currently have, and allow the government to make its case. And it would not automatically incentivise cuts like the current system does.

Other possibilities exist. As Dan Davies describes it:

any accounting system is a mental prison of some kind, and one which needs to be periodically escaped from

In my view, a jailbreak is long overdue.
A no entry sign over an image of a reverse-centaur where the robot is in control

Last month the Institute and Faculty of Actuaries (IFoA) launched what it calls its “AI Manifesto“. I thought I would take a look.

The Manifesto is admirably short and to the point. Its pitch can be summarised by this final line of its Introduction and context:

For the benefit of society, we encourage those responsible for developing and deploying AI systems to ensure that there is an actuary in the loop.

Think of it as a massive “Gissa job” plea to those companies currently investing in AI systems. But what sort of jobs are we pleading for?

The idea is that actuaries have been working with models which use machine learning for many years, that we have statistical expertise, are comfortable working with data, used to stress-testing systems and also to looking at the risk appetite of a business as a whole.

I think the first hint that there might be a problem here is when the Manifesto moves onto ethics and the public interest. As it says:

Actuaries help teams balance commercial aims with societal expectations, offering constructive solutions rather than imposing limits.

It is difficult to square this with Anthropic‘s recent IPO filing, where they warn its technology may pose “existential risks to humanity”. I am pretty confident that Society expects not to be put at existential risk. So if Anthropic thinks its technology is that dangerous, there is no balance to be found between commercial aims and societal expectations here. Societal expectations are paramount. And limits will need to be imposed rather than “constructive solutions”.

But, in my view, the main problem here is what “real world” the IFoA feel they are serving. This comes through in the role for “professionalism” they envisage:

Projects with sound validation, honest documentation and clear accountability clear governance more quickly, avoid late-stage rework, and fail in testing rather than in production. Professionalism is what lets an organisation say “yes” to AI with confidence – and protects it from the adverse outcomes that would otherwise force it to say “no”.

This, remember, is in an environment where the latest large language models like Anthropic’s Claude Opus 5.5 or OpenAI’s GPT-6 Astra, are proprietary models where validation, documentation, accountability and governance are all just what they let you see. A framework which allows companies to say yes with misplaced confidence is unlikely to be serving the public interest. And translating a capacity to apply a regulatory model to an insurance company where you have all the data and can make informed judgements about the things that you don’t know (Actuaries are used to working with large, imperfect, transactional datasets subject to audit and regulatory scrutiny. We clarify what data is needed, what quality level is acceptable, and how data should be checked, reconciled and monitored over time) is emphatically not the same as working with a model where you don’t know precisely how it works, cannot accurately predict the errors it will make and do not have enough time to look in all of the places you need to.

Take bias for instance. The Manifesto says:

We examine how a model behaves for different groups and sub-groups, test whether training data is representative of the people the system will affect, and help manage the biases we find responsibly through fairness metrics for predictive models, and output audits and red-teaming for generative systems.

Nita Farahany in the law and policy course documented in her Thinking Freely Substack demonstrates the limits of that bias management in practice, and this is Cory Doctorow on red-teaming (from Red Team Blues):

That’s the problem with blue teaming it—you need to be perfect, while—The red team only has to find a single error

Yes, that’s right, the IFoA haven’t even understood that they are on the Blue Team when it comes to AI errors, ie the one supposed to be stopping as many of them as possible. The Red Team breaks into systems by exploiting a single vulnerability. That is comparatively easy. The Blue Team needs to reassure its clients that it has removed ALL vulnerabilities.

That will be the role of any “actuary in the loop”. And the chances are it won’t be possible. The three examples given by the IFoA are as follows:

A generative AI customer assistant
An insurer wants an LLM-based assistant to answer customer queries. An actuary designs the evaluation
framework: a curated test set of realistic queries, explicit tolerances for error, escalation rules for high-stakes topics, and live monitoring of answer quality. The project clears internal governance at the first attempt because approvers can see exactly what “good enough” means and how it is evidenced.

A machine-learning decision model
A lender deploys an ML model to score applications. An actuary tests behaviour across customer sub-groups,
identifies a data artefact that disadvantages one segment, and works with the data science team to correct it. The documentation of that judgement becomes the centrepiece of a constructive conversation with the regulator.

AI risk across an organisation
A Chief Risk Officer faces AI adoption in a dozen business units at once. An actuary helps articulate an enterprise AI risk appetite, maps where the organisation depends on the same foundation models, and builds board reporting that distinguishes experimentation from deployment. The organisation accelerates adoption in low-risk areas precisely because it now knows where the high-risk areas are.

None of these examples look unreasonable in isolation, but, to justify the eye-watering expense of this technology, it will need to increase speed and capacity significantly. So, rather than a single generative AI customer assistant, imagine a client relationship management role where a junior actuary or senior student manages 10 times the current expected number of clients at the same time, because the generative AI customer assistant makes that possible?

Will the skills of an actuary versed in the intricacies of Solvency 2 or pensions regulation be so revered by your client that you would be given more than enough time to rubber stamp a system serving 30 or 40 clients? How long do you think you’d need to check the output on all of them properly? I think it unlikely you will be given that long.

This is the risk of becoming a reverse centaur, where you work for the assistant rather than the other way around. And my view is that the actuarial education system is positively encouraging the development of reverse centaurs amongst our current students.

It gets worse. The early evidence suggests that working with AI systems encourages rubber stamping. In one study of AI-generated audits with an auditor in the loop, 150 of the 160 reports were submitted without any changes made by the human. The performance of humans in the loop may also be adversely affected by working with AI systems, leading to “agency decay”:

Agency decay is the gradual erosion of a person’s ability and willingness to observe carefully, think independently, choose deliberately, and act responsibly. It does not arise because AI is inherently harmful. It arises when convenience becomes the default setting for cognition. A tool that first helps us think can begin to think around us, then for us, then without us noticing what has been weakened.

There are lessons to be learned from other professions who have been working for much longer with expert systems. The aviation industry for example. As Craig Bright, Co-Chief Operating Officer at Barclays has posted:

So the test shouldn’t be whether a human appears somewhere on the process map.

It’s whether the system remains understandable, controllable and recoverable when the agent is wrong, uncertain or unavailable.

Safety doesn’t come from leaving a human in the loop.

It comes from designing a system the human can still control.

The IFoA’s position appears contradictory. On the one hand, they clearly don’t believe that AI is as powerful or as dangerous as Anthropic are claiming in order to push up the IPO share price, or I assume they would not be pushing so hard to get an actuary on every team “developing and deploying AI systems”. I think they are right not to believe it, for a number of reasons, but Naomi Alderman’s AI predictions: seven ways you can tell useful thinking from sci-fi fantasies gives probably the most entertaining ones.

On the other hand, if this is just another technology for which the price is going to need to adjust to reality at some point, we need to be very careful as a profession not to be part of the mob urging their clients to adopt it at a faster rate than they would otherwise. Particularly if it is damaging our own professionals in the process.

AI in some form will survive the inevitable crash, but the shape and scope of the wreckage that will be left behind is currently hard to predict. Let’s be careful what we wish for.

Climate campaigners get very irritated with media talking about the “new normal”, pointing out, quite reasonably, that for it to be the new normal would require a degree of climate stability that we have not got, nor have any prospect of getting while we continue to argue about whether net zero (the policy, remember, which is about moving us to a position where we don’t increase the amount of carbon in the atmosphere year after year) is affordable. Poverty and health campaigners got very irritated by the call to “get back to normal” after the pandemic, when it had so clearly demonstrated how our “normal” way of organising society had failed to protect so many of its citizens. As even I could see in March 2020:

My view is that some things that must be different post COVID are already clear. I think as a society we are going to demand more resilience, for example:

  • Resilience of our health service – this means much higher levels of spending, building deliberate over-capacity into the system in normal times;
  • Resilience of our food supplies, for example strengthening domestic supply chains;
  • Resilience of our population, so that we do not have 1.6 million food parcels needing to be given out in a year by the Trussell Trust, in the absence of a pandemic, for instance; and
  • Resilience of our infrastructure – to everything from floods to banking crises to pandemics to storms and heatwaves.

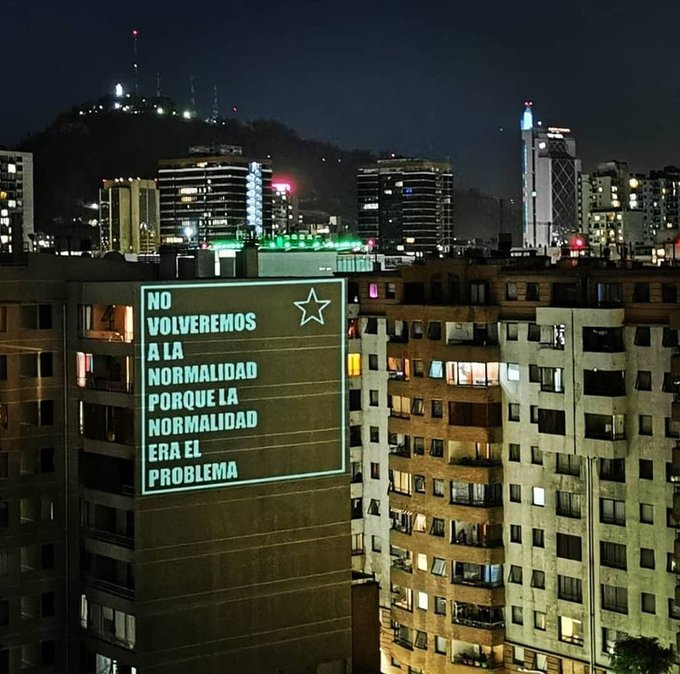
A picture circulating at the time of a Santiago apartment block with a projection onto it of “No volveremos a la normalidad porque la normalidad era el problema” (we won’t get back to normal because normal was the problem) was actually taken the previous year when the Chilean President had used the word “normality” to justifying lifting the state of emergency, leading to large protests:

Source: https://x.com/inesmorsantos/status/1190192093165211648?ref_src=twsrc%5Etfw%7Ctwcamp%5Etweetembed%7Ctwterm%5E1190192093165211648%7Ctwgr%5E%7Ctwcon%5Es1_&ref_url=https%3A%2F%2Fodi.org%2Fen%2Finsights%2Fcovid-19-we-wont-get-back-to-normal-because-normal-was-the-problem%2F “We won’t go back to normal, because ‘the normal’ was the problem.”

But we all have trouble with fast moving situations, or even just moving situations. Remember the media coverage in the early weeks of Covid utterly focused on the number of cases going up each week rather than on the underlying pattern this showed, which had been predicted and could be responded to.

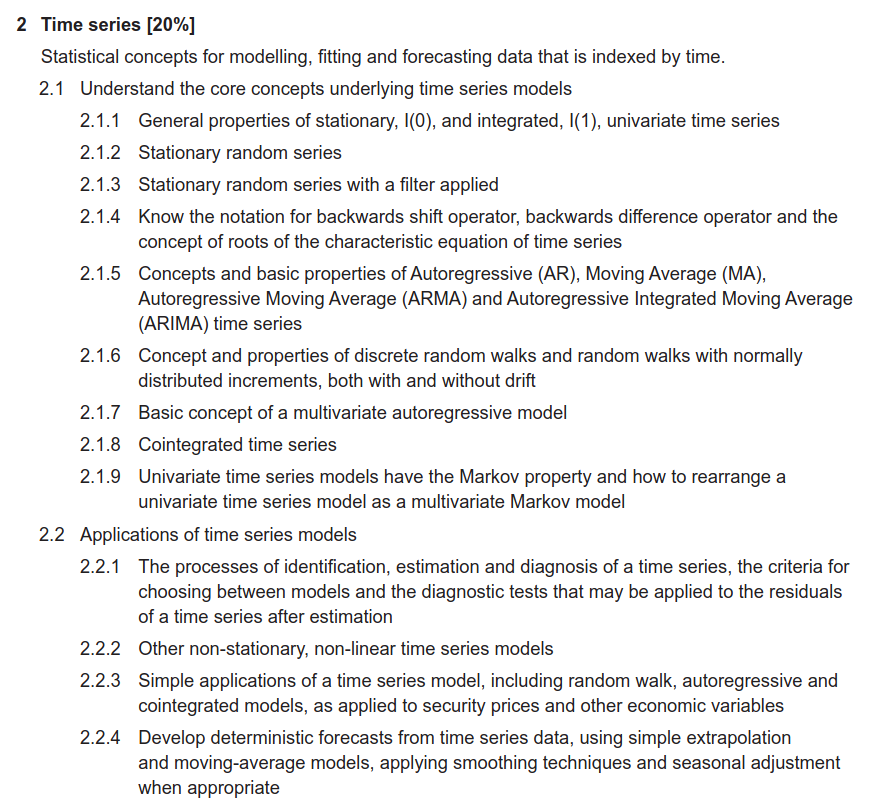
In the Institute and Faculty of Actuaries syllabus, subject CS2 Risk Modelling and Survival Analysis has 20% of its content on dealing with our trouble with moving situations via time series:

It boils down to a number of tricks to turn our moving situation into a non-moving or stationary situation, which we can then analyse.

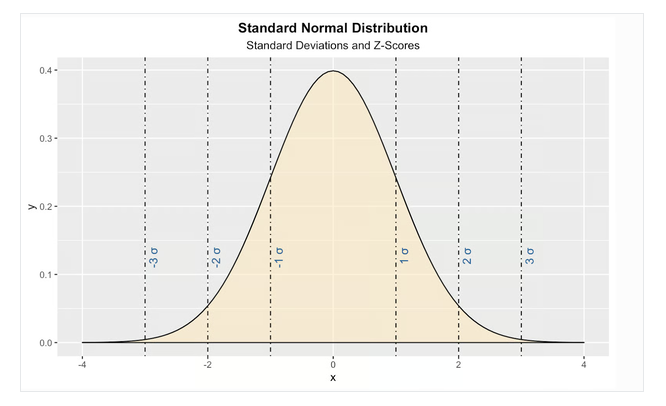
So not being able to deal with things that aren’t stationary is entirely normal. Indeed the Standard Normal Distribution, originally developed in response to a gambler’s query and another thing that we spend a lot of time transforming other distributions into if we can, has a fixed mean of 0 and a fixed variance (a measure of how far things stray from the mean) of 1:

Outside statistical analysis, we use different techniques to make things appear normal. Denial, ie ignoring the departure from normality, is a big one. When this one is no longer tenable in the face of mounting evidence that we are not in Kansas anymore, we often try and depict where we have got to as normal now. This will have been a good strategy in the past: once a natural disaster has passed, taking stock of what has been lost and what remains and working within these new parameters makes more sense than hankering back to how things were before the disaster struck.

However this strategy comes unstuck when one or both of two things are true:

  1. The disaster, or change-event more generally, is not a one-off but a continuing process.
  2. The way we were living before the disaster made the disaster more likely.

So, on climate change, both 1 and 2 are true. On the pandemic, 2 (if you define the disaster as the number of people who died during it, which I do) is clearly also true. And, although it may not be a continuing process, none other than the former Chief Scientific Advisor to the UK Government regards another pandemic as “inevitable”.

We have built systems to look at past disasters and, in particular, try and guard against 2. The Covid Inquiry is working its way through the evidence about the pandemic, and has already produced definitive evidence on how we could do things differently for those who wish to read it, but the reporting of its work is patchy, with sometimes unhelpful fixations on the wrong thing.

And denial tends to fight back as our go-to defence mechanism, which is why we often seem to need to have Public Inquiries about the same things again and again and again.

It is all quite normal. That is the problem.

Isaac Newton may or may not have been nutted by an apple. His friend William Stukeley, whose memoir of Newton was the source of the story, states it as follows (spelling and punctuation from Stukeley’s manuscript at the Royal Society):

“why should that apple always descend perpendicularly to the ground,” thought he to him self: occasion’d by the fall of an apple, as he sat in a comtemplative mood: “why should it not go sideways, or upwards? but constantly to the earths centre? assuredly, the reason is, that the earth draws it. there must be a drawing power in matter. & the sum of the drawing power in the matter of the earth must be in the earths center, not in any side of the earth. therefore dos this apple fall perpendicularly, or toward the center. if matter thus draws matter; it must be in proportion of its quantity. therefore the apple draws the earth, as well as the earth draws the apple.”

However there may be stronger grounds for believing that Newton nutted English mathematics and, as a result, the actuarial profession.

I thought all this to myself, occasion’d by participation in the Actuarial Teachers and Researchers Conference (ATRC) this week. It was great. There were lots of interesting talks, and people were very engaged and respectful in how they discussed them. There was a lot of expertise in the room about both education and actuarial practice and theory. It felt like it was a room that could take on difficult topics and make progress in tackling them.

There were several calls for the need to change assessment, one of them by me, whether due to large student cohorts and the difficulties of engaging them, or the ease with which AI can duplicate examination solutions or because the credentials provided by those assessments seem increasingly irrelevant to the actual actionable skills, knowledge and experience required to operate successfully as an actuary. And there was an equally robust response from the Institute and Faculty of Actuaries (IFoA) to the effect that assessments would not be changing significantly in the latest changes due to come in by 2029.

My favourite presentation was by Angus Macdonald, about his recent short paper on Newton, Leibniz and Actuarial Science. It conjectures that the argument between Leibniz and Newton over who invented calculus resulted in the stagnation of mathematics in English universities and meant that actuaries needing to gain respectability for their advice were forced to create a professional body (in company with architects, accountants and engineers) rather than rely on universities to develop actuarial thinking as happened in continental Europe. This stagnation (Macdonald quoted G.H.Hardy, talking about the Cambridge mathematics exams, saying that they had “. . . effectively ruined serious mathematics in England for a hundred years”) was felt across the whole Anglosphere, with attempts to create institutions with equal status to the traditional universities leading to the establishment of business schools in the USA in the late 19th and early 20th centuries.

This explained a lot for me. The suspicion of our actuarial courses amongst some of our mathematics colleagues at times at Leicester. The occasionally uneasy relationship between the IFoA and the accredited universities where students can gain exemptions from their exams. The horror from some at the very idea that an actuary might qualify as a result of university courses, like they can in the Netherlands, for instance. ATRC seemed the appropriate place to explore these ideas.

Angus Macdonald considers that the Newtonian and Leibnizian branches have nearly rejoined, but I feel that our actuarial education system still suffers from the long shadow cast by these two 17th century gentlemen and their personal enmity. The ferocity with which some within the profession opposed what they saw as a threat to the popularity of the fellowship qualification posed by the new chartered actuary designation was hard to explain when the number of practising certificates issued for chief actuaries, pension scheme actuaries, etc was only around 1,100 (out of over 17,000 fellows), but if the whole profession originated from a highly developed form of status anxiety compared to academics, it becomes much easier to understand. As they say, the apple doesn’t fall far from the tree.

Now, nearly 180 years on from this “unstoppable” “rush to respectabilize” (according to Jeremy Paxman) I think it is legitimate to ask:

  1. Why does the IFoA still insist on detailed accreditation of individual university courses on basic mathematics, statistics and business economics? Do they not trust them to teach them right? Do they think that there is something better about learning these universal subjects via a bespoke course created by a tiny professional body with 34,000 members globally?
  2. Why are they so concerned about what assessment methods the universities use? Do they consider that they have more educational expertise on this than some of the leading universities in the world?

I have written previously about the changes in assessment I think are necessary and floated some ideas about where actuarial education might sit to accommodate these. My view was that the IFoA, faced with the need to innovate at all levels of its education system at a time of great uncertainty, might wish to get out of the foundational mathematics and business education tuition of the core principles subjects and leave this to the university system, in a truly Leibnizian way.

However there is a problem. The university system is facing a tough time. UK higher education is shrinking according to the UCU branch at Queen Mary’s, which has set up a a live page of all the redundancies, restructures, reorganisations, and closures taking place across the UK Higher Education (UKHE) sector. The numbers from the Higher Education Statistics Agency (HESA) bear this out, with overall student numbers falling, driven by a 10% fall in overseas entrants with a non-European Union permanent address.

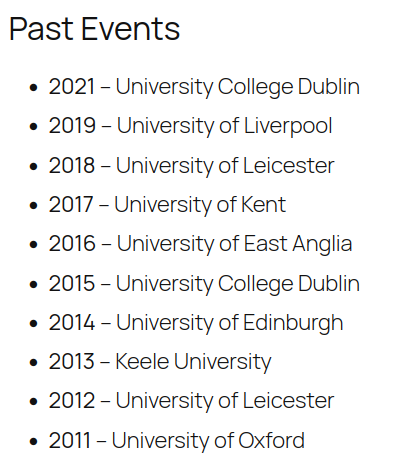
In actuarial science, the list of UK universities offering accredited courses has not changed for some time, and it is a small group within the university system. These courses must be seen as vulnerable. I don’t think it is a coincidence that it is so hard to persuade one of this tiny band to run the ATRC. This week’s was the first since 2021 and the list of past hosts is not very long:

Source: https://atrc.le.ac.uk/

The IFoA needs to ask itself what it would do if there were some high profile closures of actuarial courses and whether perhaps it might be time to protect the core mathematical education arrangements for actuaries through a broad brush accreditation of a wider range of courses, rather than the very detailed accreditation process it currently carries out on core principles subjects.

I also doubt that it has the capacity on its own to significantly restructure its assessments beyond the objective based assessments it has developed to work within its proctored environment.

The core practice and specialist subjects leading to fellowship are the areas where actuaries have, rightly, the strongest views about content and assessment structures. It surely makes sense that the expertise within the profession and the university system are pooled in a joint endeavour rather than risking both failing independently.

In contrast to Newton, who had quite a temper, Leibniz was famously parodied by Voltaire in his Dr Pangloss character in Candide who believed that “All is for the best in this best of all possible worlds.”

Let’s not be too Panglossian about the current state of actuarial education.

This week I attended one of the National Emergency Briefing screenings near me. While I wasn’t a fan of the Celebrity Gogglebox presentation style, with Chris Packham on the sofa seeing what Jennifer Saunders and others thought about the climate emergency, it did give me enough of an idea about the individual presentations to want to follow them up, and there is a really good website to do so here.

The two points which struck me particularly were the following:

  1. Professor Tim Lenton warning about what would happen if the weakening Atlantic Meridional Overturning Circulation (AMOC) hit a tipping point which, in some models, “shows that London would be -20°C in three frozen months of the year, and Edinburgh would be -30°C in five and a half frozen months of the year. And yet the summers will still be hotter than today because it’s a 2°C warmer world.”
  2. Professor Hayley Fowler warning of the risks of mega floods: “These storms can produce two thirds of a year’s rainfall in just a couple of days. Over London, that would mean about 35cm of rainfall falling over a large area. A flood of this scale will be a national crisis. Recovery would take years.” She also warned that by 2050 1 in 4 properties – 8 million in England – will be at risk of flooding.

And since flooding often follows a heatwave such as the one we are currently experiencing, I thought I would look at the risk of long-term flooding in a bit more detail, which is when I came across the government’s check the long term flood risk for an area in England website. When you put in your postcode, it assesses your flood risk under four different categories:

It then explains how they measure the risk and the kinds of things which tend to affect it. All in all a good resource, and the modelling behind it is what the 1 in 4 properties at risk of flooding by 2050 is based on.

In July 2021, several European countries were affected by severe floods. The floods started in the United Kingdom as flash floods causing some property damage. Later floods affected several river basins across Europe including Austria, Belgium, Croatia, Germany, Italy, Luxembourg, the Netherlands, Romania and Switzerland. At least 243 people died in the floods, including 196 in Germany, 39 in Belgium, two in Romania, one in Italy and one in Austria. It was thought that some of the affected regions may not have seen rainfall of this magnitude in the last 1,000 years.

A study using climate simulations on a grid of 2.2km squares published in June 2021 had come to the following conclusion:

Intense rainstorms are expected to be more frequent due to global warming, because warmer air can hold more moisture. Here, using very detailed climate simulations (with a 2.2 km grid), we show that the storms producing intense rain across Europe might move slower with climate change, increasing the duration of local exposure to these extremes. Our results suggest such slow-moving storms may be 14× more frequent across land by the end of the century. Currently, almost-stationary intense rainstorms are uncommon in Europe and happen rarely over parts of the Mediterranean Sea, but in future are expected to occur across the continent, including in the north. The main reason seems to be a reduced temperature difference between the poles and tropics, which weakens upper-level winds in the autumn, when these short-duration rainfall extremes most occur. This slower storm movement acts to increase rainfall amounts accumulated locally, enhancing the risk of flash floods across Europe beyond what was previously expected.

As Professor Fowler says:

Our infrastructure was built for a climate that no longer exists. Raised reservoirs, drainage, housing and transport were designed many years ago when extreme rainfall was rare and less severe. As rainfall intensifies, risks such as dam overtopping and cascading failures rise.

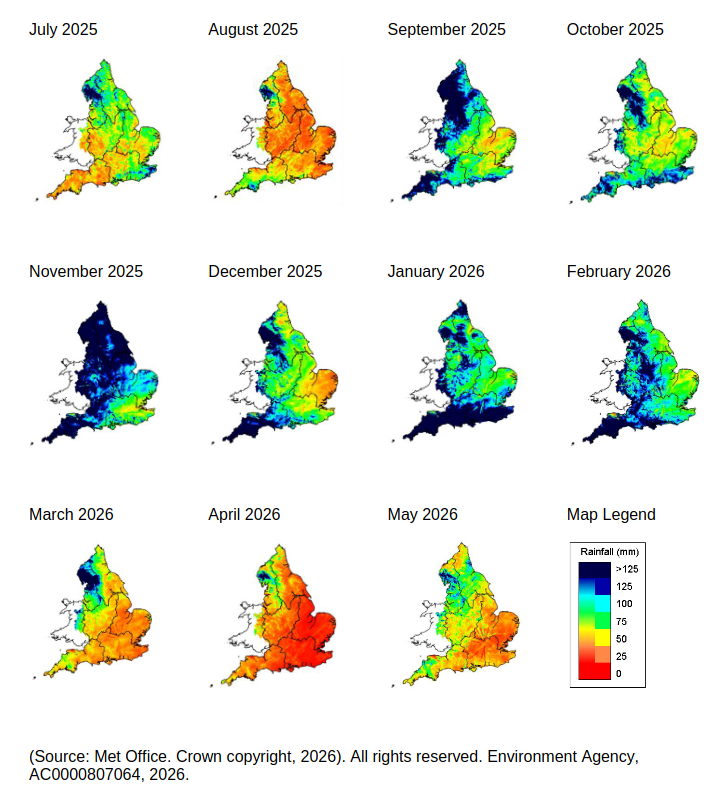
The government also produces monthly reports on rainfall, soil moisture deficit, river flows, groundwater levels and reservoir levels. This includes a wonderful map of the year’s rainfall:

What struck me was that the report looked at exactly the same things (river levels, groundwater levels and reservoirs) but, because they were concerned with low levels of rainfall, did not even mention flood risk. The rainfall scale only goes up to >125mm rainfall within a month as a maximum, which looks hilarious when compared with the 271.5mm of rainfall over 48 hours in parts of Belgium in 2021.

There have been no new reservoirs built in the UK since 1992, just another one of the gifts of water privatisation discussed previously. The government announced last year that it had “seized control of the planning process” to build two reservoirs due to be complete in 2036 in the Cambridgeshire Fens and 2040 near Sleaford in Lincolnshire respectively.

Professor Fowler says the probability of dam overtopping is increasing. So how’s the review of reservoir safety going?

In 2019, there was a failure of a dam at Toddbrook Reservoir in the Peak District. The operation to pump water out of the reservoir to safeguard Whaley Bridge seems to have been dominated by concerns about the fish. The independent review commissioned into the incident identified the rather alarming fact that:

“…the reservoir and its Owner can be compliant with the legislation without the reservoir necessarily being safe.”

Among the report’s recommendations were the following:

  • There is a systematic review of how the current Reservoirs Act, and the associated Regulations and Guidance, are implemented. This should consider the roles and responsibilities of qualified engineers, whether compliance with the Act is sufficient to ensure safety, and how safety is formally assured.
  • The potential of an Inspecting Engineer issuing a Certificate of Safe to Operate be explored. This should include a review of practice in other safety critical infrastructure sectors. It should also consider liability implications and whether some form of qualifying statement may be needed to accompany the certificate.
  • The statutory maximum period between inspections is reviewed to determine if it is still appropriate in every case in the light of the ageing reservoir stock.

In his follow up report looking at the reservoir system in general in 2021, Professor David Balmforth made this extraordinary statement:

This raises the question of what is meant by “safe”. In other infrastructure sectors and with reservoirs in other countries, safety is assured by managing risk, and by reducing that risk so far as is reasonably practicable – the terms “reasonable” and “practicable” being well understood in practice and in law. For a reservoir, risk is defined as a combination of the likely failure of the dam (or other reservoir structure) and the impact that an uncontrolled release of water would have on the area downstream, particularly the likely loss of life. I have therefore recommended that in future the assurance of reservoir safety should be managed on the basis of risk, and that the amount of effort (and cost) associated with that process should be in proportion to that risk. In this way the public can be assured that the hazard posed by reservoirs is being managed in an objective and transparent way.

It would appear that reservoir management is playing catch up on the whole concept of risk management.

What has followed is a policy paper from the Environment Agency on the launch of a reservoir safety reform programme. However the public consultation on the proposed reforms has already been delayed until later this year. And the page about the consultation process does not suggest anyone is in any hurry.

A no entry sign over an image of a reverse-centaur where the robot is in control

As I discussed in How Not To Be A Reverse-Centaur (Cory Doctorow defines a reverse-centaur as “a machine that is assisted by a human being, who is expected to work at the machine’s pace”) our actuarial education system needs to change. This has been true for some time, but the development of AI systems has both demonstrated why more clearly and accelerated the timeframes over which action is needed. As I said in December last year:

A large part of the education of the future will need to be about equipping us all to understand what we now have access to and when and how to access it. We will all have different things we are interested in, or end up involved with and needing to be educated about. It will be up to each of us to decide which things are worth the difficulty of learning, but to make those decisions we will need education that can support the development of judgement.

For education institutions, the question will be what is not worth the difficulty of learning? Credentialising based on now relatively meaningless assessment methods will not cut it. This is where the confrontation with employers and politicians is likely to come. Essential skills and their related knowledge will be better developed and assessed via more open-ended project work and online assessment of it to check understanding. These will need to become the norm, with written examinations becoming less and less prevalent. Not because of fear of cheating and plagiarism, but because an outcome which can be replicated that easily by AI is not worth assessing in the first place.

Suppose you were to ask someone who had never seen our academic system that, in order to assess whether someone else we wanted them to employ in their organisation would do a good job for them, we would:

  1. Award marks for what has been written in answer to academic questions about what the students can remember unaided about the content of their lecture courses and reading lists with a biro on a pad of paper perched precariously on a tiny wooden table surrounded by hundreds of other similar scribblers, for a set period of time as minders wandered the floors like Victorian factory owners.
  2. These marks would be based on marking criteria they would never see.
  3. We would then get together in a secret huddle for a couple of months to mark all these scripts, check them and “moderate” them to check they were in line with the previous years’ exercises.
  4. Then out would come the answer (like the Answer of 42 to the Ultimate Question of Life, the Universe and Everything in Douglas Adams’ The Hitchhikers Guide To The Galaxy).

Source: https://hitchhikers.fandom.com/wiki/42

Imagine another world where the kinds of things employers routinely do when trying to decide whether to take on someone as a new member of their organisation are routinely part of their assessments at university, eg:

  • Watch them operating in groups working on a task.
  • Ask them to describe how they would go about tackling a particular problem.
  • Get them to show they understand the implications of a piece of work they have carried out and can explain what assumptions it is based on and can justify them.

With assessments of performance which are not opaque academic exercises but descriptions of performance made as the tasks are being carried out evidenced by video if necessary. In other words, transparent enough to whoever might want to work with these students next to eliminate the gap between their credentials and and their actual actionable skills, knowledge and experience.

Assessing in this way will be highly demanding, for both the students and the assessors, but it means the final assessment is done with the student present and, with careful probing from the assessors, who will obviously need to have done a close reading of the project work beforehand, confidence will be high about the abilities demonstrated by the process. And it removes the need for all the time currently spent on the Victorian factory owner process – imagine what could be done if the whole of May, June and July wasn’t spent marking scripts!

A move like this will significantly change what is taught. There will be no point presenting lots of information in ways which make retention easier for students (the so-called bookwork” questions currently in most exams). This makes sense when you think about how much of the content of your courses is accessible to you now, even on a vocational course like actuarial science, as opposed to skills developed. Instead the focus will be more on conversations with students for the purpose of developing their understanding of a meaty topic and the problems to be solved within it. Explorations of these will form the projects students will be spending most of their time working on. Checking understanding and making sure students are working within frameworks they understand and can talk about will be the main teaching activity, with opportunities to practise these throughout the year. In other words, showing the ability to apply what they have understood and demonstrate the ability to reflect, make judgements and show higher levels of understanding as a result. An ability they can then apply to new problems and situations.

And notice something else about how these alternative credentials are generated? They are all social activities: from operating in groups, to presenting a piece of work to a group of assessors. Even the project work is developed through group sessions alongside individual work. If you want to develop people who can spot the gaps between models and reality you need to do it in groups, where people can test their perspectives against each other.

Compare this to the current solitary exam preparation, peppered with “revision” lectures, exam sitting and exam marking processes which comprise the predominant activities in universities between March and July each year. We are currently being funneled into an ever more solitary professional practice around LLMs. It has become quite accepted for people to do all of their thinking on a subject closeted with perhaps one, two or three LLMs but no other people and then share their analysis with an expectation that other people should read the output. Developing the skills to do these analyses will obviously be necessary, but they will never be the most important skills people learn.

Treating each other like walking databases is never going to make you new friends or influence people. However the skills you develop via an alternative more social education will.

There are examples of this approach already happening, with employers involved in the design of assessments in some cases and universities using the flexibility they have to restructure and redesign courses. But the dominant assessment system of formal exams is keeping much of this activity at the margins at the moment.

If it were to become the dominant assessment, it would also mean that larger areas of the curriculum could be examined, as the focus would not be on retention of large bodies of content but the ability to use the content to solve problems. So, perhaps, after a first year levelling up students’ ability and experience of mathematics and statistics, year 2 would have an actuarial statistics module (currently CS1/CS2) and an actuarial mathematics module (currently CM1/CM2), both dissertation based and vivaed. Then in the third year they would tackle an economics module and a business modules (currently CB1 and CB3). Perhaps in the final year of a four year MAct they would tackle a modelling and communication module (CP2/CP3) and either CP1 actuarial practice module would be offered or a professional skills module.

This would be more of a driving test style of assessment, with students working with supervisors on the comments from assessors on the original dissertations and presentations until they were up to the required standard. Students unable to make the standard after an additional year would be offered a move to a non-accredited course. The current funding model for higher education will need to change: loading students with £10,000 more debt every time they add to the nation’s skills bank with another year wrestling with these difficult skills to master was never a clever strategy, but this structure would make it even clearer how self defeating it is. If economists are accepting that the labour market no longer allocates resources effectively and are considering either a universal basic income or universal basic services, then logically university funding should follow suit.

The implications for the actuarial profession will be even more challenging. I question whether the Institute and Faculty of Actuaries will continue to consider it worth the effort and expense of reconfiguring their entire approach to exam setting, syllabus maintenance, marking, online proctoring, etc for subjects routinely taught throughout the university system for a a variety of purposes, ie the current core principles subjects of mathematics, statistics and business studies.

Whether they retain their own capacity to assess the core practice subjects is a more open question (CP1 Actuarial Practice, I imagine, will be seen as sufficiently specialist to keep in house, with perhaps a few universities, as now, accredited to run courses which can earn this qualification, however CP2 Modelling and CP3 Communications are not nearly as specialised now as they seemed when they were first introduced). I would also move the new core economics module recommended by the IFoA Economics Review Group I chaired in 2022 to replace the current CB2 module into the core practice section, as it would be more of a critical thinking module about the economic ideas necessary to underpin good actuarial work than the technical how-to subjects in core principles.

The specialist stage of the SP and SA subjects and the whole continuing education and additional certification options I would confidently expect the profession to retain, review and adapt as needed to reflect new challenges in members’ working lives. However, if CP1 is all that is needed post graduation to get to Chartered Actuary and CP1, two SP subjects and a SA subject gets you to Fellow, then suddenly time to qualification becomes much more predictable for students and their employers alike.

The risks to employers of taking on students would therefore be reduced, but also the rewards to taking them on will be much more transparent. The students we will be developing will have collapsed the gap between their credentials and their actual actionable skills, knowledge and experience. They will have:

  • Great team working skills;
  • Very highly developed presentation skills, both in writing and speech;
  • Strong IT skills and comfort working with data; and
  • Clarity about why they are in an organisation and a drive to use their skills to solve problems.

They will also have developed the four capabilities set out in Carlo Iacono’s Teach Judgement, Not Prompts:

  1. Epistemic rigour. They will be more likely to spot when a system or model is over-confident given the evidence, after an intense experience of interrogating models and evaluating evidence in their courses.
  2. Synthesis. They will be able to integrate different perspectives into an overall understanding, through dissertation development, defending a position, understanding weaknesses in a position and adjusting accordingly.
  3. Judgement. They will have been asked to make many judgements in their work and had to defend them in discussions with their supervisors and fellow students. Unconvincing opinions, not backed by evidence, will not pass muster.
  4. Cognitive sovereignty. Students will have to take their own stand on their work, after all of the challenge and argument. Independence of thought is the hard-earned outcome here.

And then they will have a fighting chance of being centaurs in the world awaiting them, masters of the technology and opportunities available, rather than the reverse-centaurs that our education system is currently, and inadvertently, preparing them to be.

A suited pinhead wearing a pirate's hat stands in the stern of a pirate ship below a dangling ladder
Source: Nick Foster – December 2013 – originally drawn to deride George Osborne’s austerity as Pugwash Economics, repurposed now as I am worried about the actuarial profession pulling up the ladder on the next generation

The “black box” was a constant refrain when I was working as an actuarial consultant. It was where the results from a process were being accepted without any understanding of how they were arrived at. Something we felt that any self-respecting actuarial consultant should challenge in their own work and everybody else’s.

However when you came to actually present analysis or arguments to a client, you expected a certain amount of that expertise to be taken as read, to effectively be inside a black box as far as the client was concerned. They couldn’t be expected to understand all of the aspects of what you were talking about, otherwise they wouldn’t need you. Good practice was always to put them in a position where they could understand and make decisions about the key aspects of your advice without needing to engage with the other parts. As the expert, you decided what was in the black box.

Now the black box is back with a vengeance for all the professionals who have relied upon them in their working lives. As Dan Davies puts it:

The same black-box property which stops you from being second guessed or overruled means that nobody is interested in your explanations for your decisions; it is definitional of being a black box that you are going to be judged by results.

And, if you are in the business of advising in the teeth of uncertainty, as actuaries are, then this is likely to be a real problem. If noone cares how your advice was constructed, but they can get advice that ticks the compliance box your client has to complete more cheaply and quickly than you can, the more automated black box is going to win the business. The experienced professional still has a role in managing this process, verifying the results coming out of the black box and determining what can still be kept out of the black box, but he may be increasingly struggling to justify the cost of his junior colleague.

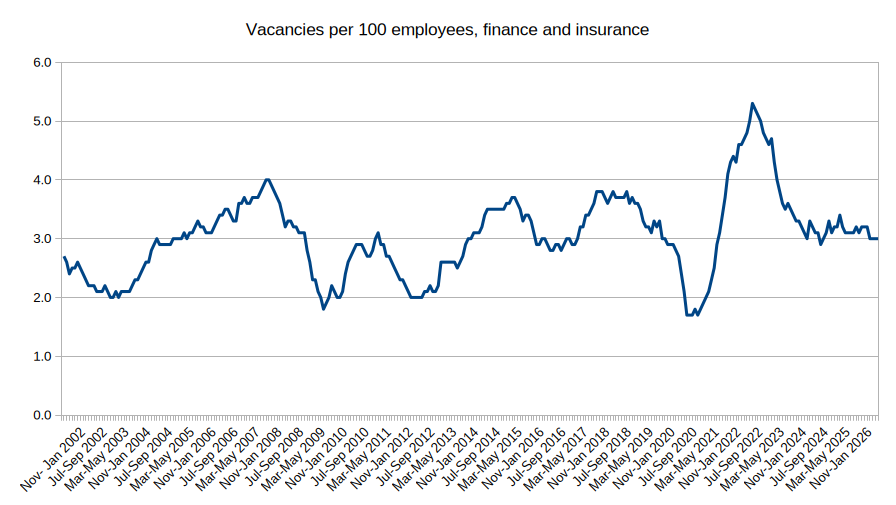
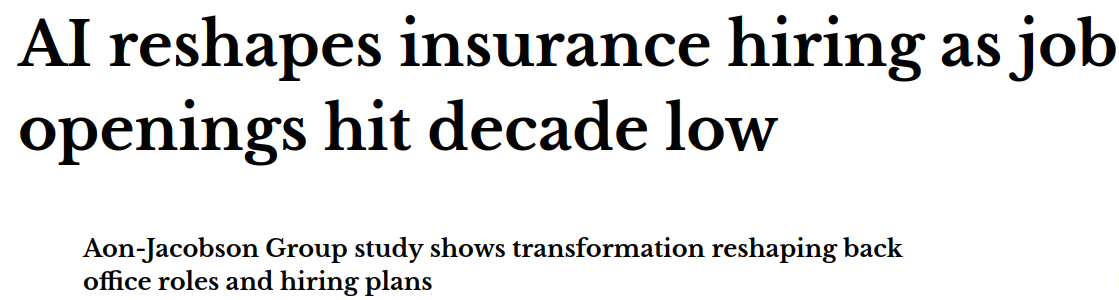
I wrote about how devastating the fall in graduate job listings was 9 months ago, so where have we got to since?

Well things don’t look so bad in the UK right now according to the Office for National Statistics (ONS), reverting to close to the average after a post pandemic surge in the finance and insurance sector:

Source: https://www.ons.gov.uk/employmentandlabourmarket/peoplenotinwork/unemployment/datasets/vacanciesbyindustryvacs02

However, if we look at the United States, which tends to show us where the UK finance sector is going, it looks far more ominous:

Yesterday Sky News ran a story about Standard Chartered‘s CEO who, in his desperation not to describe over 7,500 job losses as cost cutting, said this:

It’s not cost-cutting. It’s replacing in some cases lower-value human capital ​with the financial capital and the investment capital we’re putting in.

We may need to sit with that statement for a little while.

Daniel Susskind talks about this risk in his latest lecture entitled A World Without Work: in summary, to paraphrase only slightly, sure relatively junior white collar roles may already be particularly hard hit by AI, but he is optimistic because of the impact on GDP and we cannot pause because of China. He then goes on to talk about the four problems he sees for a post AI future:

  1. Distribution (replacing wages);
  2. Contribution (how do you “pull your weight”);
  3. Power (domination by Big Tech on economics, politics, liberty, social justice and democracy); and
  4. Meaning (fulfilment in life).

Susskind has gone from thinking that the fear that AI is coming for your jobs was overblown and that it was just task encroachment that we faced, to now thinking that it may encroach on all the tasks in most fields. Jevons Paradox (that technological innovation that increases the efficiency of a resource’s use leads to a rise in consumption of that resource) is no comfort if that new demand is robot-met.

Carlo Iacono suggests that the move of junior roles to AI may be subtle to begin with:

The weakness among young workers may appear as fewer people entering employment from outside the workforce. Firms may not fire large numbers of juniors; they may simply hire fewer of them.

That matters. The labour market can look healthy while the entry path narrows. Senior workers stay employed. Output rises. Productivity improves. There is no dramatic wave of redundancies.

Yet the first rung is being taken out.

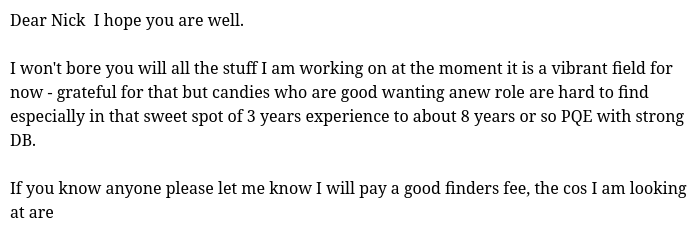
It may also be masked by the fact that there remains a shortage for actuaries beyond the entry roles. There is almost a hint of desperation to approaches like this looking for introductions from a retired actuary like myself:

(followed by a list of clients he is working for)

Source: recruitment consultant who will remain anonymous. I am assuming “candies” are candidates

And, even if you think the risk of the AI Bubble bursting soon, taking down the global stock markets underpinned by the Magnificent 7, is exaggerated, you do need to be suspicious about the current abilities of AI to replace junior staff. My experience with another, somewhat earlier, actuarial technology, the pensions valuation engine, would suggest that the outputs need to be analysed very carefully before sharing with a client: it often had dependencies between what should have been independent variables hidden in the programming, or vagaries in the setup which left out non-standard benefit rules for your particular scheme, for instance. Or the student who had set it up initially (a complicated process usually) might have made a mistake or you might have not communicated with them very well to start with. Or a hundred other things.

For whatever reason, there was often still a lot to do after the valuation engine had produced some output.

Can this sort of thing happen with agentic AI? Well think about that student programming the valuation engine, but on steroids. Its patchy capabilities combined with its basic psychopathy leads to, as Hannah Fry entertainingly demonstrates here, some serious problems arising with the agent’s relentless to and fro with the large language models it depends upon, asking them what it should do next. As Hannah says:

I built an AI agent. She opened a shop selling novelty mugs, emailed a journalist without being asked, and then leaked our passwords to a total stranger.

As Kyle Kingsbury wrote about having an AI agent as a colleague in a programming team:

Imagine a co-worker who generated reams of code with security hazards, forcing you to review every line with a fine-toothed comb. One who enthusiastically agreed with your suggestions, then did the exact opposite. A colleague who sabotaged your work, deleted your home directory, and then issued a detailed, polite apology for it. One who promised over and over again that they had delivered key objectives when they had, in fact, done nothing useful. An intern who cheerfully agreed to run the tests before committing, then kept committing failing garbage anyway. A senior engineer who quietly deleted the test suite, then happily reported that all tests passed.

You would fire these people, right?

Yet despite all this, the money continues to pour in to the construction of AI infrastructure. There are already websites up and running for all of the parts of tasks AI cannot encroach upon.

Source: https://rentahuman.ai/

The bottom rung of the actuarial ladder is clearly in danger. This is a particular problem for the actuarial profession, which has traditionally relied on longer periods of work-based training for its future qualified actuaries than many other professions. Training to become an actuary takes a long time. Median time to fellowship is still around six years, with some taking up to ten or giving up. The exams are hard to pass. There have been attempts by the profession to tackle some of these disincentives: the Chartered Actuary designation to make a destination of the generalist qualification before the specialisation of the fellowship, championed on this blog and launched in the teeth of opposition by some fellows, being one example.

It has led to a culture within actuarial firms around managing the extended time in training, with rituals around study leave and results days. One of the fears expressed in opposition to the introduction of the Chartered Actuary designation was that, if this could be achieved almost entirely within formal education at universities, the value of working alongside experienced actuaries would be lost.

It has led to a culture within the profession itself of managing large parts of its education system in house. Half of its revenue and around 30% of its expenditure are on “pre-qualification learning and development”. Sometimes it looks more like an education business with a professional side hustle.

But then the new AI toys have come along, and it turns out that many of those experienced actuaries may be less keen on graduates coming in and needing supervision from them after all. Many of them may rather spend hours on AI prompts than on developing another human being.

I fear that, increasingly, companies are not going to accommodate actuarial students in their work plans without significant persuasion. And, if the number of students studying while in work falls, the profession itself is going to struggle to finance its own bespoke education system at an acceptable cost to its members.

It will be hard for the profession to challenge this too: it is going to be good for many of those already established in their roles as the market for more experienced actuaries, when the market has no interest in developing the actuaries of the future, becomes increasingly competitive.

If the actuarial profession does accept the challenge of protecting the pipeline of future experienced actuaries it will need to review its entire education syllabus through this lens. It will also need to engage with other partners involved in what is in effect a problem of capital formation and collective action: government incentives may be needed to encourage firms to continue to train early career professionals and discourage free-riding. There may be no way back for the student with no actuarial qualifications learning on the job. The universities may be needed to plug people in at a different career point, which will require them to innovate themselves even further into the professional training role than ever before. As Carlo Iacono points out:

educational institutions may be pushed to simulate more of the apprenticeship environment. That does not mean adding a thin “AI literacy” module. It means creating settings where students practise judgement under uncertainty, in realistic workflows, with feedback that is close enough to hurt and useful enough to teach.

It will not be at all easy. But the alternative is a future without opportunity for those who do not already have it and an ageing profession withering on the vine it refused to nurture.

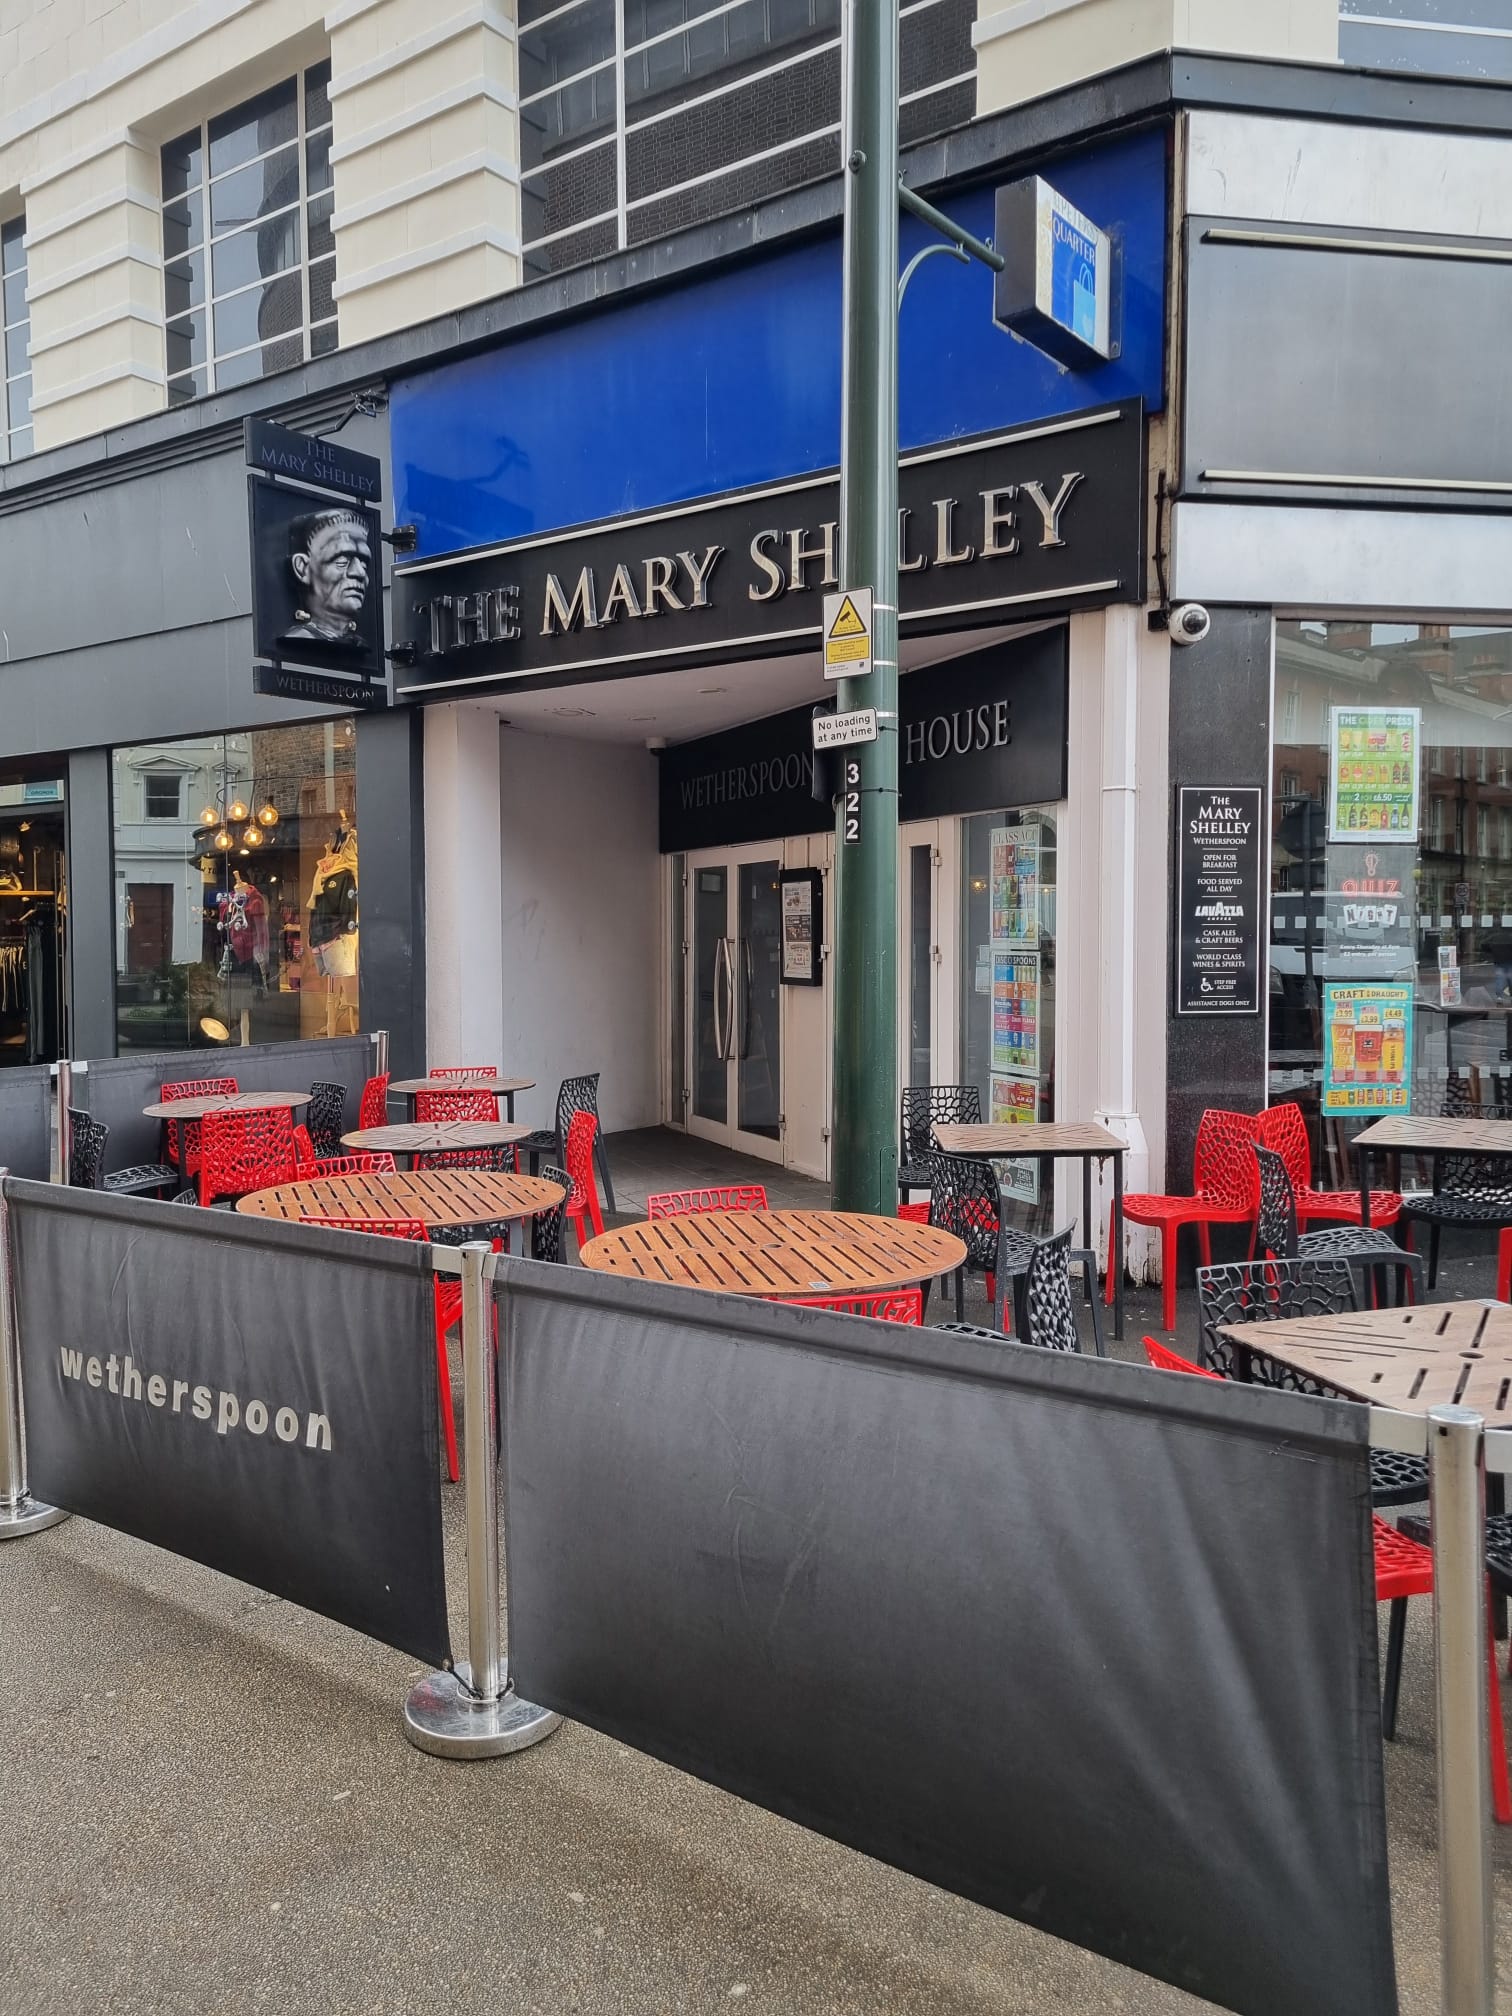
The Wetherspoons pub The Mary Shelley in Bournemouth

A few months ago I decided to read Mary Shelley’s Frankenstein for the first time. I also watched Guillermo del Toro’s Frankenstein, on a big screen, despite, according to The New Yorker, it having been “Netflixed down to size”.

Shelley’s book is largely monologues of interior thoughts of Frankenstein and his creation, with wildly careering emotions and death, death, death everywhere – perhaps unsurprising from an author whose mother died 10 days after giving birth to her, who lost a child and whose half sister died by suicide while she was working on Frankenstein, with much more tragedy to follow after its publication. There is a word Mary Shelley uses more than I have read in any other book: variants of sympathy/sympathise/sympathies turn up 32 times. Because of course one of the many things the book is all about is mutual incomprehension of the creator and the created.

Last week I was in Bournemouth as a last minute substitute for Lanzarote, something I may come back to at a later date, and I stumbled across the churchyard of St Peter’s Church in which Mary Shelley was buried, along with the cremated heart of her husband Percy Shelley, at the age of 53. There is also a pub in Bournemouth named after her (above) but whose sign depicts the monster from her most famous piece of writing.

As we enter another time of mutual incomprehension of the creator and the created, I have been reading the surprisingly-difficult-to-access paper by Kyle Kingsbury (the systems engineer, not the MMA guy) called The Future of Everything is Lies, I Guess. I will put a link to an X account which shared it here, as going to the aphyr.com site to read it seems to generate this message:

Once you can read it though, it starts to sketch out a likeness of our current monster and chip away a little at the human side of the mutual incomprehension. I am talking, of course, about what people are currently calling “AI”, which Kingsbury defines as:

…a family of sophisticated Machine Learning (ML) technologies capable of recognizing, transforming, and generating large vectors of tokens: strings of text, images, audio, video, etc. A model is a giant pile of linear algebra which acts on these vectors. Large Language Models, or LLMs, operate on natural language: they work by predicting statistically likely completions of an input string, much like a phone auto-complete. Other models are devoted to processing audio, video, or still images, or link multiple kinds of models together.

The article sets out how this is a technology where nobody really understands why it has been successful or how to make it better, which falls into strange loops or attractors, has odd gaps in its capabilities and is highly sensitive to slight changes in its formatting. It is a technology which is simultaneously highly capable and an idiot. And Kingsbury worries that our culture is not ready for such a technology. As he says:

As LLMs etc are deployed in new situations, and at new scale, there will be all kinds of changes in work, politics, art, sex, communication and economics. Some of these effects will be good. Many will be bad. In general, ML promises to be profoundly weird.

Buckle up.

He continues:

Most people seem concerned with conscious, motivated threats: AIs could realize they are better off without people and kill us. I am concerned that ML systems could ruin our lives without realizing anything at all.

There follow extensive examples of the problems the various ML applications are already starting to cause and some speculation about where things may be going in various areas of our lives before we get to the chapter on work. And the subject of hiring “AI employees”. This is probably my favourite bit:

Imagine a co-worker who generated reams of code with security hazards, forcing you to review every line with a fine-toothed comb. One who enthusiastically agreed with your suggestions, then did the exact opposite. A colleague who sabotaged your work, deleted your home directory, and then issued a detailed, polite apology for it. One who promised over and over again that they had delivered key objectives when they had, in fact, done nothing useful. An intern who cheerfully agreed to run the tests before committing, then kept committing failing garbage anyway. A senior engineer who quietly deleted the test suite, then happily reported that all tests passed.

You would fire these people, right?

Kingsbury sees the two extremes of the possible range of outcomes as:

  1. ML systems continue to hallucinate, cannot be made reliable, and ultimately fail to deliver on the promise of transformative, broadly-useful “intelligence”. Or they work, but people get fed up and declare “AI Bad”…a lot of ML people lose their jobs, defaults cascade through the financial system, but the labor market eventually adapts and we muddle through. ML turns out to be a normal technology.
  2. In the other extreme, OpenAI delivers on Sam Altman’s 2025 claims of PhD-level intelligence, and the companies writing all their code with Claude achieve phenomenal success with a fraction of the software engineers. ML massively amplified the capabilities of doctors, musicians , civil engineers, fashion designers, managers, accountants, etc, who briefly enjoy nice paychecks before discovering that demand for their service is not as elastic as once thought, especially once their clients lose their jobs or turn to ML to cut costs. Knowledge workers are laid off en masse and MBAs start taking jobs at McDonalds or driving for Lyft, at least until Waymo puts an end to human drivers. This is inconvenient for everyone: the MBAs, the people who used to work at McDonalds and are now competing with MBAs, and of course bankers, who were rather counting on the MBAs to keep paying their mortgages. The drop in consumer spending cascades through industries. A lot of people lose their savings, or even their homes. Hopefully the trades squeak through. Maybe the Jevons paradox kicks in eventually and we find new occupations.

In the following chapter Kingsbury speculates on what some of those new occupations might be:

  • Incanters. People who can prompt LLMs into getting what is wanted.
  • Process Engineers. People who help catch LLM errors. They build quality control processes – training people, identifying where more intense review is needed, assessing the cost-benefit trade offs of automating tasks, etc
  • Statistical Engineers. People who try and measure, model and control variability in ML systems.
  • Model Trainers. This will become increasingly difficult as the amount of false content or “slop” increases across the internet.
  • Meat Shields. People who are accountable for the errors of the ML systems they supervise.
  • Haruspices. People responsible for going through the model inputs, outputs and internal states of a ML system which has done something terrible to try and give a plausible reason for its behaviour.

But ultimately Kingsbury concludes that we should just stop using these systems. To return to the original analogy, the monster cannot be understood. There is often nothing actually there to understand. And it is certainly not in the business of understanding you. Although it may be very very good at convincing you otherwise.

On balance I think my view is currently at the muddle-through-with-ML-as-a-normal-technology end, which still looks likely to cause a disruption considerably bigger than 2008. My main reason is the already collapsing trust in many of the Big Tech companies. Trust which is going to be required even if their technology really can do some of this stuff. It is the scenario where we all get fed up and declare “AI Bad”. Like when we read about the people running Meta showing nowhere near the social responsibility commensurate with their current level of market power.

Or when, as last week, we have days and days of breathless commentary about Anthropic’s Mythos and Project Glasswing, and how its immense capabilities caused the company not to release it, sparking a meeting of central bankers to discuss the threat such technologies posed to financial systems. Only to finally read an account of attempts to verify any of what Anthropic have been saying. It is quite a technical piece, which I by no means understand all of, but the final paragraph is fairly arresting:

The most important thing in the Mythos release is not the model. It is the precedent. Anthropic has established, without discussion and without pushback, that a private company can unilaterally classify a capability as too dangerous for the public, grant selective access to the largest incumbents in the affected industry, and construct a parallel disclosure regime outside any democratic accountability structure. That precedent is exclusivity for abuse. It will be used by companies with worse judgment than Anthropic and narrower definitions of “partner” than the Glasswing consortium. The time to object to the shape of this thing is while it is still being built, not after it has removed all transparency and accountability.

How might Claude or ChatGPT respond to being designated “AI Bad”? Well Mary Shelley’s monster put it this way:

Once I falsely hoped to meet with beings who, pardoning my outward form, would love me for the excellent qualities which I was capable of unfolding. I was nourished with high thoughts of honour and devotion. But now crime has degraded me beneath the meanest animal. No guilt, no mischief, no malignity, no misery, can be found comparable to mine. When I run over the frightful catalogue of my sins, I cannot believe that I am the same creature whose thoughts were once filled with sublime and transcendent visions of the beauty and the majesty of goodness. But it is even so; the fallen angel becomes a malignant devil. Yet even that enemy of God and man had friends and associates in his desolation; I am alone.

Front page of the April 2026 issue of Brum Group News

Three and a half years ago, I wrote a piece likening the rapid climate change on Earth to the fairly well-established science fiction concept of terraforming, but in reverse. So what has happened since? Well last summer, according to researchers at Imperial College and the London School of Hygiene and Tropical Medicine, two thirds of the 24,400 heat deaths from June to August across Europe were due to human-made global heating. And a study published last month has suggested that the pace of global warming has nearly doubled since 2015.

It this point I would like to suggest rehabilitating an old word to describe this process, in the opposite direction to terraforming (which is action designed to make a planet more habitable). Barrenize means to make barren or sterile and was used between the mid 1600s and the early 1700s according to the Oxford English Dictionary, originally in the context of animal husbandry. I think it’s time to bring this word back.

In a week when a US President has threatened, variously, “blowing everything up and taking over the oil” and that Iranians would be “living in Hell”, to last night saying that “a whole civilisation will die tonight”, unless they opened the Strait of Hormuz, it certainly sounds like a commitment to barrenization to me, only at a faster pace than the global warming he is already doing everything possible to accelerate further.

On Friday this week, the Birmingham Science Fiction Group will have Oliver Bettis as its guest speaker. Oliver has been a leading actuary in the field of sustainability for many years. He is one of the authors of a series of publications by the actuarial profession in collaboration with the University of Exeter in recent years.

Climate Scorpion shows how we need to develop a best guess about the worst-case scenarios and make policy on that basis, given our lack of knowledge about extreme climate risk and tipping points.

Planetary Solvency – finding our balance with nature sets out an approach to civilisational risk management which attempts to address the fact that the severity and frequency of extreme events are unprecedented and beyond current model projections.

Parasol Lost, which we will be discussing in particular this Friday, focuses on the cooling effect of aerosols: a side-effect of pollution from fossil fuel burning. Without aerosol cooling the global temperature would be around 0.5°C higher than the 1.4°C increase above pre-industrial temperature that we have today. It is critically important to recognise that, as air pollution is cleaned up, this may ironically lead to a short-term increase in warming through the loss of aerosol cooling. The question must be asked, can we afford to lose this cooling and if not, should this be replaced by working with nature, using technology or both?

This will allow us to tap into the rich history of science fiction literature on terraforming (and dealing with the threat of barrenization) and whether this can allow us to look at this question in a new way. It should be a lively discussion.

This event will be held in-person at the Friends of the Earth Warehouse, 54-57 Allison Street,
Birmingham B5 5TH and simultaneously on Zoom, with online access opening from around 7.45 for an 8 pm start.

Ticket prices for non-members are £8 for in-person attendance and £6 for Zoom attendance. For members it’s £4 in-person attendance and free Zoom attendance.

Tickets can be purchased on the door or via the Eventbrite link below:

https://www.eventbrite.co.uk/e/1985958692911

And if this whets your appetite for more science fiction and you think you might like to join the group, just email us at contact@brumsfgroup.org.uk. Hope to see you there!

OK I don’t know if this is a remotely helpful post, but it really feels to me like one of those months we will look back on, like March 2020, and wonder what we were thinking. To recap: on 4 March 2020, while Italy were shutting all their schools and a month after the WHO had declared a global health emergency, we were noting that the number of cases in the UK had jumped from 53 to 87 in one day.

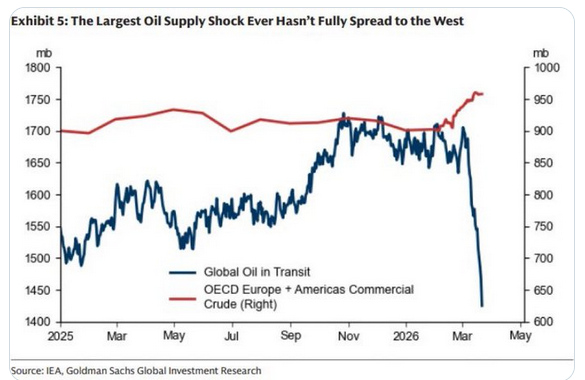
Jump forward to now and the number of tankers with oil on board is in freefall:

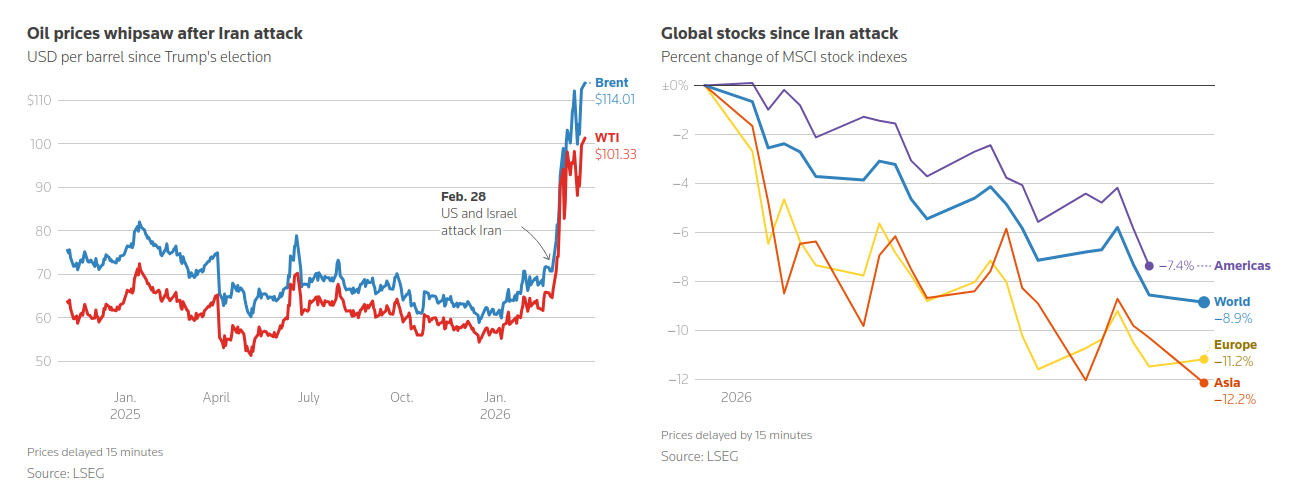
Trump is talking about invading Kharg Island and “obliterating” Iran’s energy facilities, and we are sitting in the time lags of international fossil fuel freight waiting to see what will happen. But we already know what is going to happen. Just like the pandemic, we will be taking similar measures to the countries already more affected very soon. The order looks like Asia, followed by Africa, then Europe and only then, ironically, the United States.

So what is going on in Asia right now? Well the Philippines announced a national energy emergency six days ago, setting up an authority to oversee the orderly distribution of fuel, food, medicines, and other essential goods. Sri Lanka has announced a four-day week for all government employees. Egypt is ordering restaurants, cafés and shops to close at 9pm to safeguard dwindling energy reserves. Slovenia has brought in fuel rationing. Moldova’s Parliament has also voted to impose a state of emergency in the country’s energy sector. Australia is offering free public transport. Measures are also being taken in Thailand, Ethiopia, Myanmar, Vietnam, Bangladesh and South Sudan.

On 3 March 2020, the UK Government unveiled their Coronavirus Action Plan, which outlined what the UK had done and what it planned to do next. Paul Cosford, a medical director at Public Health England, said widespread transmission of COVID-19 in the United Kingdom was “highly likely”.

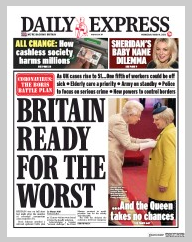
On 4 March 2020, the Daily Express were telling us:

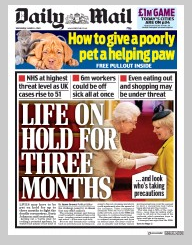
Which we clearly weren’t. Meanwhile the Daily Mail was anticipating future lockdowns and 6 million people being off sick:

The next day we had the first Covid death in the UK. And life was on hold for the next two years.

Our response to the energy crisis seems to be almost entirely focused on

1. The cost-of-living crisis; and

2. The financial markets.

The Education Secretary has said that motorists should fill up as normal as the government is “well prepared” for disruption. The trouble is, many of us still remember September 2000:

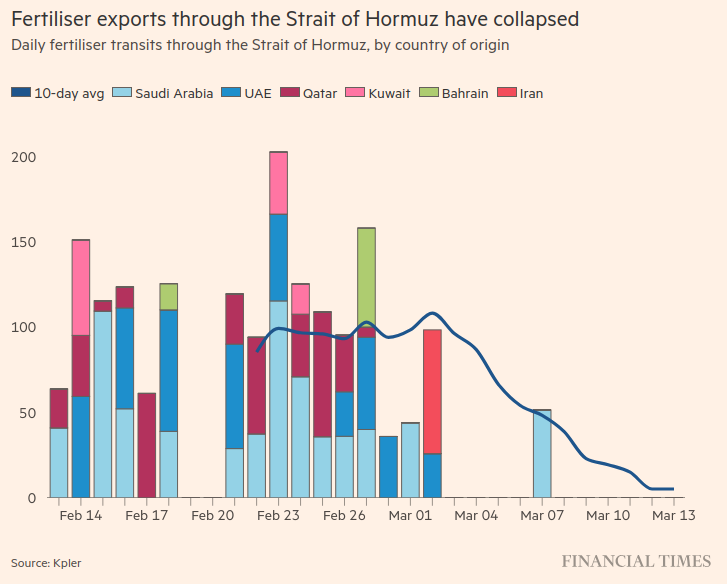
So that would be enough to make us all feel nervous about shortages and queues for everything, having our lives disrupted and out of our control. But the real potential issue is not even being talked about, certainly not by the government. It is a shortage of food. Steve Keen sets out the economics of global food production here. This does not tend to feature prominently in mainstream economic analyses which are energy and food blind for the most part, although the FT did have this graph a couple of weeks ago:

As Steve Keen says:

Survival will depend on grain reserves. China has of the order of 18 months in reserve, which will insulate it from the disruptions of 2026. The USA and India have substantial reserves as well, but some countries—including the UK—have virtually none.

…Famines will ensue, and even countries that have never experienced such events could be forced into food rationing. This includes the UK and Australia, and a patchwork of countries across Europe.

This is what people are nervous about: not being able to get enough food, either because it isn’t available at all or not at a price they can afford. Calling that a cost-of-living crisis is a bit like calling the Black Death a labour market crisis. And it doesn’t stop there. As Steve Keen continues:

Other critical products that normally pass through the Strait of Hormuz include Helium, which is critical to the production of semiconductors, and sulphuric acid, which is critical to numerous production processes. The closure of the Strait cuts off one third of global helium output and about half of global sulphuric acid output.

With critical industrial inputs cut as well, the problems will cascade well past food alone—though that is clearly the most damaging impact. With LNG, petroleum, helium and sulphuric acid production cut, the capacity to undertake repairs to damaged facilities will also be hindered.

The TED War is rather like smashing a spider’s web—and then killing the spider.

The spider certainly looks in a poor state of health at the moment, and parts of the web will take years to fix. This is the crisis we are all inevitably going to be entering in the next few weeks. For who knows how long.

A risk management approach to this crisis would involve communicating a plan to the country that minimised the impulse to hoard resources and protected the most vulnerable from extreme prices, rather than bland reassurances from government ministers. We need this to be in place very quickly now.